The Agoda 'Pay Later' Trap: Dodging the 5% Exchange Markup and Claiming Real Cash
Why guaranteed rates spike on auto-debit day: exposing internal exchange spreads and reclaiming cold hard bank deposits.
The Book Now Pay Later Illusion and the 5% Morning Forex Shock
The Book Now, Pay Later option presented alongside free cancellation terms represents the ultimate digital travel temptation. It promises zero upfront capital commitment and delivers immense psychological comfort when travel dates remain fluid. The booking interface reassuringly announces: 'Amount due today: $0. Estimated charge on October 15: approximately $450.' Naive travelers routinely assume this settlement converts at fair institutional interbank rates on billing morning.
However, the moment credit card push notifications flash at dawn on payment day, travelers confront severe sticker shock. Accommodations originally quoted at $450 abruptly clear at $474, silently packing a markup exceeding 5%. On a 3-night urban stay running $1,200, more than $60 vanishes overnight. Crucially, global currency markets never fluctuated by 5% during that interval.
The mechanics lie buried inside platform contractual disclosures. Scrutinizing the fine print reveals that choosing Pay Later explicitly exempts the transaction from official central bank reference benchmarks. Instead, billing converts via proprietary internal exchange algorithms that systematically tack on an approximate 5.0% spread above institutional Reuters baseline rates.
| Payment Route | Pay Later (Delayed Auto-Debit) | Pay Now in Native Currency | Real Savings ($1,000 Booking) |
|---|---|---|---|
| Conversion Index | Proprietary Platform Rate (+5.0% Spread) | Interbank Mid-Market Benchmark | ~$50 Immediate Saving |
| DCC Forex Spread | High Risk of 3% to 8% Markup | 0% (Clean Foreign Currency Debit) | ~$30 to $80 Protected |
| Card Network Surcharge | ~1.2% Overseas Fee | 0% (Via Zero-FX Multi-Currency Cards) | ~$12 Network Waiver |
| Total Settled Amount | $1,062 to $1,142 Settled Equivalent | $1,000 Net Flat | Up to $142 (14.2% Total Edge) |
Travelers effectively surrender substantial cash premiums for the illusion of postponement. Worse, merchant receipts never disclose this cost as a discrete line-item fee. The entire markup melds seamlessly into the nightly room tariff, ensuring 99% of cardholders remain blissfully unaware of the financial leakage.
Dynamic Currency Conversion (DCC): Evading Redundant Multi-Tier Spreads
Erecting a defense against unexpected billing fees begins with the checkout currency selector. Millions of international travelers leave default home currencies (USD, GBP, EUR, AUD) untouched simply because domestic numbers feel familiar. Doing so steps directly into the predatory apparatus of Dynamic Currency Conversion (DCC).
Because the booking engine operates as an offshore merchant gateway, requesting charges in domestic tender forces a multi-tier conversion carousel. The hotel native tariff converts first into intermediate clearing indices before re-converting into home currency. Payment gateways and clearing houses pocket between 3% and 8% in redundant cross-border forex spreads on the round trip.
The antidote is absolute: lock the settlement currency strictly into the destination legal tender. Choose Japanese Yen (JPY) across Japan, Thai Baht (THB) throughout Thailand, Vietnamese Dong (VND) in Vietnam, Euros (EUR) across the Eurozone, and US Dollars (USD) for international properties elsewhere. The foreign figures look unfamiliar on screen, but the ultimate net debit remains undeniably lowest.
Pairing specialized multi-currency travel debit cards (Wise, Revolut) with immediate native-currency payment completely eliminates intermediary FX margins. For traditional credit cards, activating 'Block Foreign DCC' inside your banking app establishes an automated mechanical safeguard, instantly declining transactions attempted in domestic tender.
AgodaCash vs Real Bank Cashback Rewards: Dissecting True Economic Value
Auditing rate tables frequently reveals green promotional badges highlighting either 'Cashback Rewards' or 'AgodaCash'. While marketing copy portrays them as interchangeable perks, their economic realities diverge drastically. Failing to discern the difference forfeits hundreds in cold hard cash.
AgodaCash represents a closed-loop virtual credit balance trapped within platform walls. It carries razor-thin expiration windows spanning three to six months and routinely caps redemption at 10% to 20% of subsequent reservations. Conversely, 'Cashback Rewards' deliver authentic fiat currency wired directly into your checking account or credited back to your card statement following checkout.
| Metric | AgodaCash (Virtual Points) | Cashback Rewards (Liquid Cash) |
|---|---|---|
| Liquidity | Locked inside platform ecosystem | Direct wire transfer to domestic bank checking account |
| Expiration | 3 to 6 months (Rapid forfeiture) | 120 days claim window following activation |
| Usage Constraints | Blocked on flash deals and major chains | Pure liquid cash with zero merchant restrictions |
| Realized Value | Roughly 50% to 60% face value | 100% face-value institutional fiat currency |
On a $1,500 luxury stay in Singapore returning $180 in Cashback Rewards, real accommodation overhead drops to $1,320. This penetrates far below the cheapest public quotes indexed by Google Hotels or major comparison engines.
However, algorithms never disburse these funds automatically. Post-checkout, travelers must manually trigger the claim flow within designated claim windows and input routing credentials. Missing the deadline by a single day forfeits the balance permanently into platform profit margins.
Mobile App Exclusives vs Desktop Bank Conduits: The Cross-Audit Rule
Launching smartphone apps triggers glowing banners boasting '10% Mobile Exclusive Discount'. The digital travel populace instinctively equates mobile screens with rock-bottom pricing. Rigorous pricing audits expose this assumption as deeply flawed.
Telemetry audits reveal mobile discounts frequently apply atop base rates artificially inflated by 8% to 12%, resetting prices back to normal market baselines. Conversely, entering desktop web portals via dedicated banking conduits (Visa, Mastercard, premium issuer CID links) accesses uninflated baseline inventories and unlocks genuine 7% to 12% instant ledger deductions.
Across extended stays exceeding three nights or high-value vacation reservations surpassing $1,000, desktop banking conduits consistently undercut mobile app totals. Furthermore, premium room tiers including executive lounge privileges and complimentary buffet breakfasts often remain exclusively bookable on desktop partner portals.
Execute a 3-step cross-audit. First, record the all-inclusive mobile price. Second, launch an incognito desktop session through your credit card partner conduit. Third, compare final checkout figures side-by-side. Three minutes of auditing routinely saves enough cash to fund an exceptional omakase dinner.
The 5-Step SOP to Reclaiming 100% of Bank Cashback Rewards
Returning home from overseas travel plunges anyone into work backlogs, making past hotel receipts easy to forget. Commercial algorithms bank heavily on human forgetfulness. Statistics indicate a staggering percentage of OTA cashback expires uncollected. Securing these funds demands an ironclad operational routine.
Step one: On checkout day, register a smartphone calendar reminder set exactly 60 days ahead. Cashback requires an audit buffer to verify authentic stays, shifting status from 'Pending' to 'Claimable' at the two-month mark. Label the alert with the specific dollar figure owed.
Step two: When the reminder fires, navigate into the app account menu under 'Cashback Rewards'. Tapping the active claim trigger opens the bank transfer ledger. Enter your bank clearing code, account number, and English passport name with surgical accuracy to prevent wire rejections.
Step three: Verify the one-time authentication passcode sent to your registered email address. Once authorized, international electronic wire transfers clear into domestic checking accounts within 3 to 5 business days. Evading delayed auto-debit spreads, neutralizing DCC, and capturing bank cashback ensures you always sleep well below market floor rates.
Frequently Asked Questions
Field-tested answers to transit navigation, neighborhood choices, and payment traps.
Q1.What is the exact exchange markup applied to Agoda Pay Later bookings?
Q2.Is it cheaper to pay in domestic currency or the hotel local currency?
Q3.When can Cashback Rewards be claimed and how is the money transferred?
Q4.Is it always cheaper to book via the mobile app or a desktop browser?
The Smart Traveler's Essential Toolkit
Prepare instant mobile data, private airport transfers, and skip-the-line passes in one place.
Pick a base in Singapore by your route
Choose the places you want to see and get the neighbourhood with the shortest travel.
Compare Singapore Hotel Rates
Find the cheapest channel across Agoda and major booking engines with Tripdify.
Share This Guide with Your Companions
When shared via chat or social media, a curated summary card is sent along.
Recommended Guides
Before Regretting a 13-Sqm Shoebox: The Tokyo 3-Zone and 14-Day Booking Playbook
Comparing room footprints across Shinjuku, Ginza, and Ueno, locking in sudden 14-day cancellation drops, and eliminating DCC fees with clean Yen checkout.
Tokyo Value Hotels Playbook: 7 Smart Yamanote Stays, Onsen Baths and OTA Rate Hacks
Even amid yen fluctuations, central Tokyo hotel rates have soared. Learn how to secure Yamanote loop line hotels at half the price of Shinjuku, compare onsen bath chains like Dormy Inn, trigger secret Agoda VIP and Booking.com Genius discounts, and dodge hidden currency fees with yen settlement.
Tokyo Transit Survival Blueprint: Airport Rail Hacks, Metro Pass Math, and Yamanote Hubs
How to choose between Keisei Skyliner and Narita Express, avoid the Tokyo Subway Ticket trap, use Apple Wallet Suica, and select the ideal hotel base in Tokyo.
Tokyo Day 1 Arrival Blueprint: Narita Skyliner, Frictionless Ramen, and 24-Hour Settlement
From stepping off at Narita Airport to mastering high-speed trains, navigating Tokyo's sprawling transit hubs, ordering counter ramen effortlessly, and catching sunset from Roppongi Hills. A definitive guide for your first 24 hours in Tokyo.
Tokyo Day 2 Iconic Sights Playbook: Shibuya Sky Sunset Booking, Harajuku Alleys, and Roppongi Nightscapes
Securing prime sunset slots atop Shibuya Sky, navigating hidden boutiques along Harajuku Cat Street, immersing in the forested serenity of Meiji Jingu, and marveling at the crimson glow of Tokyo Tower from Roppongi Hills. A masterclass in Day 2 pacing.
Tokyo Day 3: Asakusa Heritage, Akihabara Pulse, Ginza Depachika, and Seamless Airport Departure
The ultimate finale for your Tokyo stay: tranquil morning worship at Sensoji, retro subculture in Akihabara, Ginza Six architectural rooftop views and basement depachika feasts, capped by seamless Skyliner and N'EX airport connections.
Osaka 72-Hour Feast: Dotonbori Canal Neon, Kuromon Market & Umeda Heights
Osaka is Japan culinary powerhouse where feasting is an art. Navigate Rapi:t airport transfers, Namba vs Umeda hotels, and street food corridors with veteran precision.
Kyoto Arashiyama & Gion Retreat: Historic Ryokans and Early Dawn Bamboo Groves
Kyoto compresses a millennium of Japanese aesthetic mastery. Discover how to evade bus congestion with private railways, master ryokan kaiseki booking windows, and savor early dawn stillness.
Kyoto Ryokan & Machiya Masterclass: Kaiseki Economics, Sukiya Timber, and Quiet Alleys
From hundred-year-old timber townhouses in Gion to misty Arashiyama riverside ryokan, staying in Kyoto demands cultural fluency and sharp booking discipline. An honest receipt audit covering kaiseki dinner curfews, private onsen etiquette, and avoiding dynamic pricing spikes.
Kyoto Day 1 Arrival Playbook: 75-Minute Haruka Express, Station Luggage Delivery, and Gion Twilight
Boarding the 75-minute Haruka Express from Kansai Airport, forwarding heavy bags straight to your hotel via Crosta at Kyoto Station, avoiding gridlocked buses using the subway, and an evening stroll through Gion to the Kamogawa. A field guide to your first 24 hours.
Kyoto Day 2: Fushimi Inari Torii Path, Kiyomizu-dera Heights, Ninenzaka Lanes, and Gion Kaiseki Feast
Day 2 immerses travelers into the spiritual heartbeat and preserved historic streets of Kyoto: early morning solace along thousands of vermilion torii gates at Fushimi Inari, sweeping mountain panoramas from the legendary wooden stage of Kiyomizu-dera, artisan tea shops and matcha sweets across cobblestoned Ninenzaka and Sannenzaka, followed by lantern-lit strolls in Gion Shirakawa and a refined multi-course Kaiseki dinner.
Kyoto Day 3: Arashiyama Bamboo Grove, Tenryu-ji Zen Pond, Nishiki Market, and Haruka Airport Express
A sublime final chapter to your Kyoto journey: morning breezes whispering through towering emerald stalks in the Arashiyama Bamboo Grove, the UNESCO World Heritage mirror pond at Tenryu-ji, riverside specialty coffee by Togetsukyo Bridge, savory culinary treasures inside 400-year-old Nishiki Market, followed by Kyoto Station souvenir shopping and a swift 75-minute ride aboard the JR Haruka Express straight to Kansai Airport.
Bangkok 72-Hour Field Guide: Chao Phraya Sunsets, Street Food & Hotel Strategy
Master Bangkok with confidence: airport express logistics, Riverside vs Sukhumvit accommodation bases, temple morning protocols, and cashless GLN QR payments.
The Definitive Bali Field Guide: Ubud Jungles, Coastlines & Split-Stay Playbook
Navigate Bali with ease: electronic visa tricks, private airport transfers, Ubud jungle villas vs Canggu coastal suites, and Nusa Penida speedboat crossings.
Interlaken & Jungfrau Field Guide: Alpine Passes, Eiger Chalets & Glacier Trails
Master Switzerland's Bernese Oberland: Top of Europe ascent routes, Swiss Travel Pass vs Jungfrau VIP Pass comparisons, Lauterbrunnen hikes, and DCC currency savings.
Florence 72-Hour Renaissance Field Guide: Duomo Climbs, Uffizi & Tuscan Tables
Navigate the cradle of the Renaissance: skip-the-line museum tickets, 463-step Duomo climbs, artisan Oltrarno stays, and DCC credit card savings.
Venice 72-Hour Water City Guide: St Mark's Piazza, Vaporetto Boats & Island Stays
Master Italy's floating city: skip costly single-ride fares with timed boat passes, navigate Burano routes, discover bàcaro wine bars, and dodge hidden DCC card fees.
Haussmann Balconies and Seine Twilight: Parisian Boutique Hotels and Transit Blueprint
How to budget for unexpected Parisian municipal taxes, choose boutique stays between Le Marais and the Latin Quarter, and master CDG airport transit with Navigo Easy.
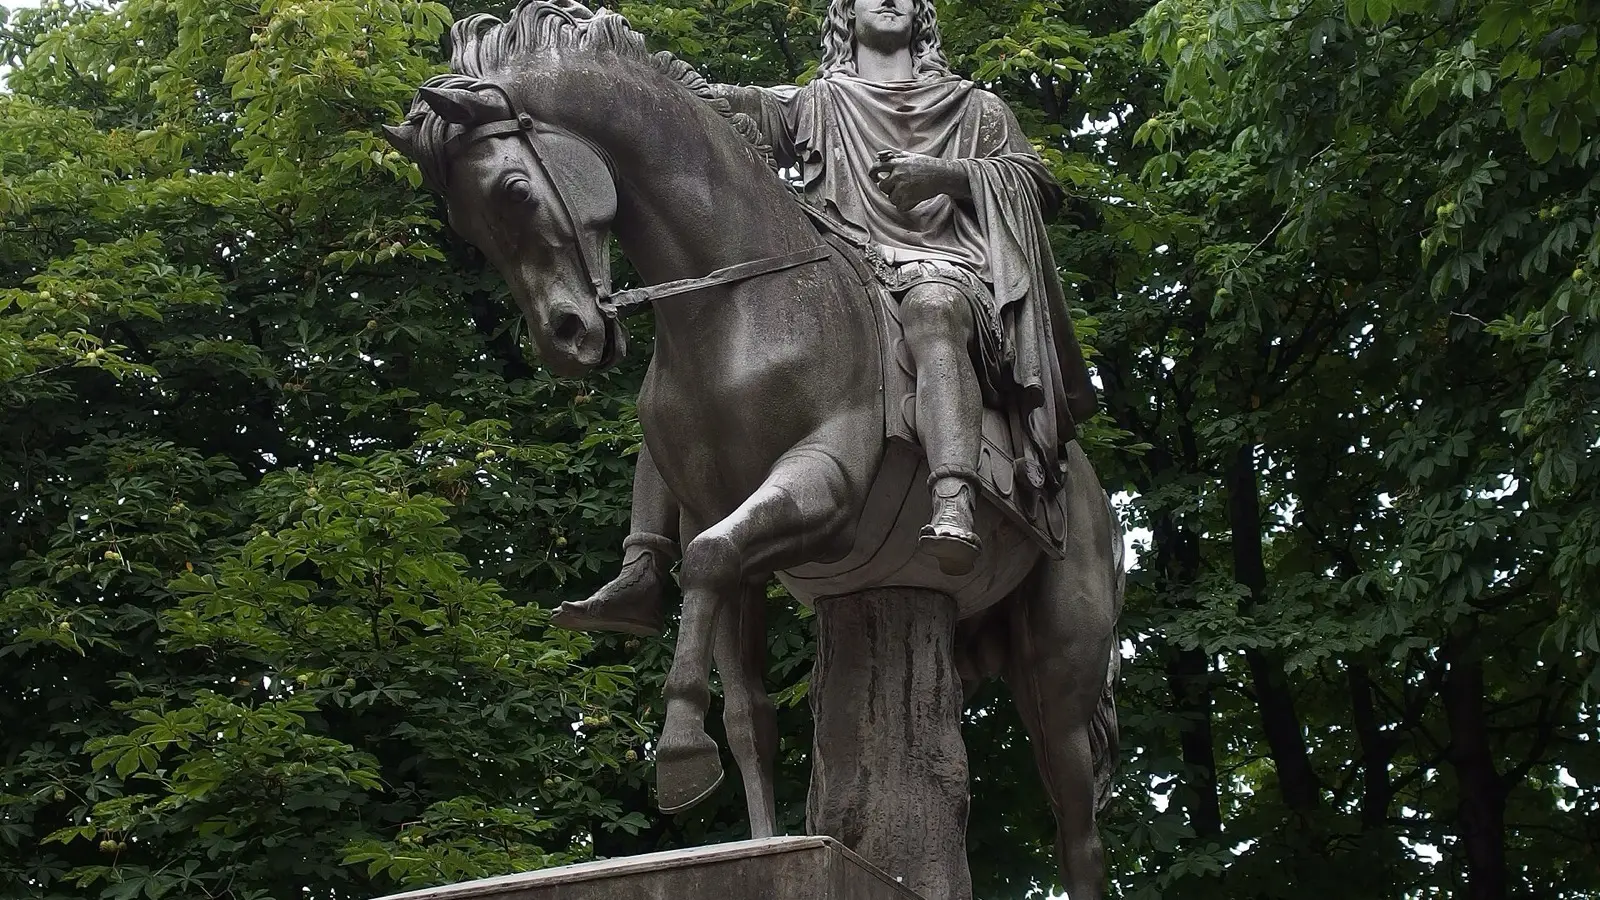
Paris 20 Arrondissements Field Guide: Safe Stays, Dodging Tourist Tax Hikes, and Metro Pickpocket Evasion
Behind the postcards of the Louvre and the Seine lies a city of stark contrast, sudden tourist tax spikes, and vast neighborhood disparities. Spanning 20 arrondissements spiraling clockwise from the historic core, choosing the right basecamp dictates whether your trip feels like a romantic dream or an exhausting obstacle course. Here is the definitive field guide to securing safe, value-packed Parisian lodging with local mastery.
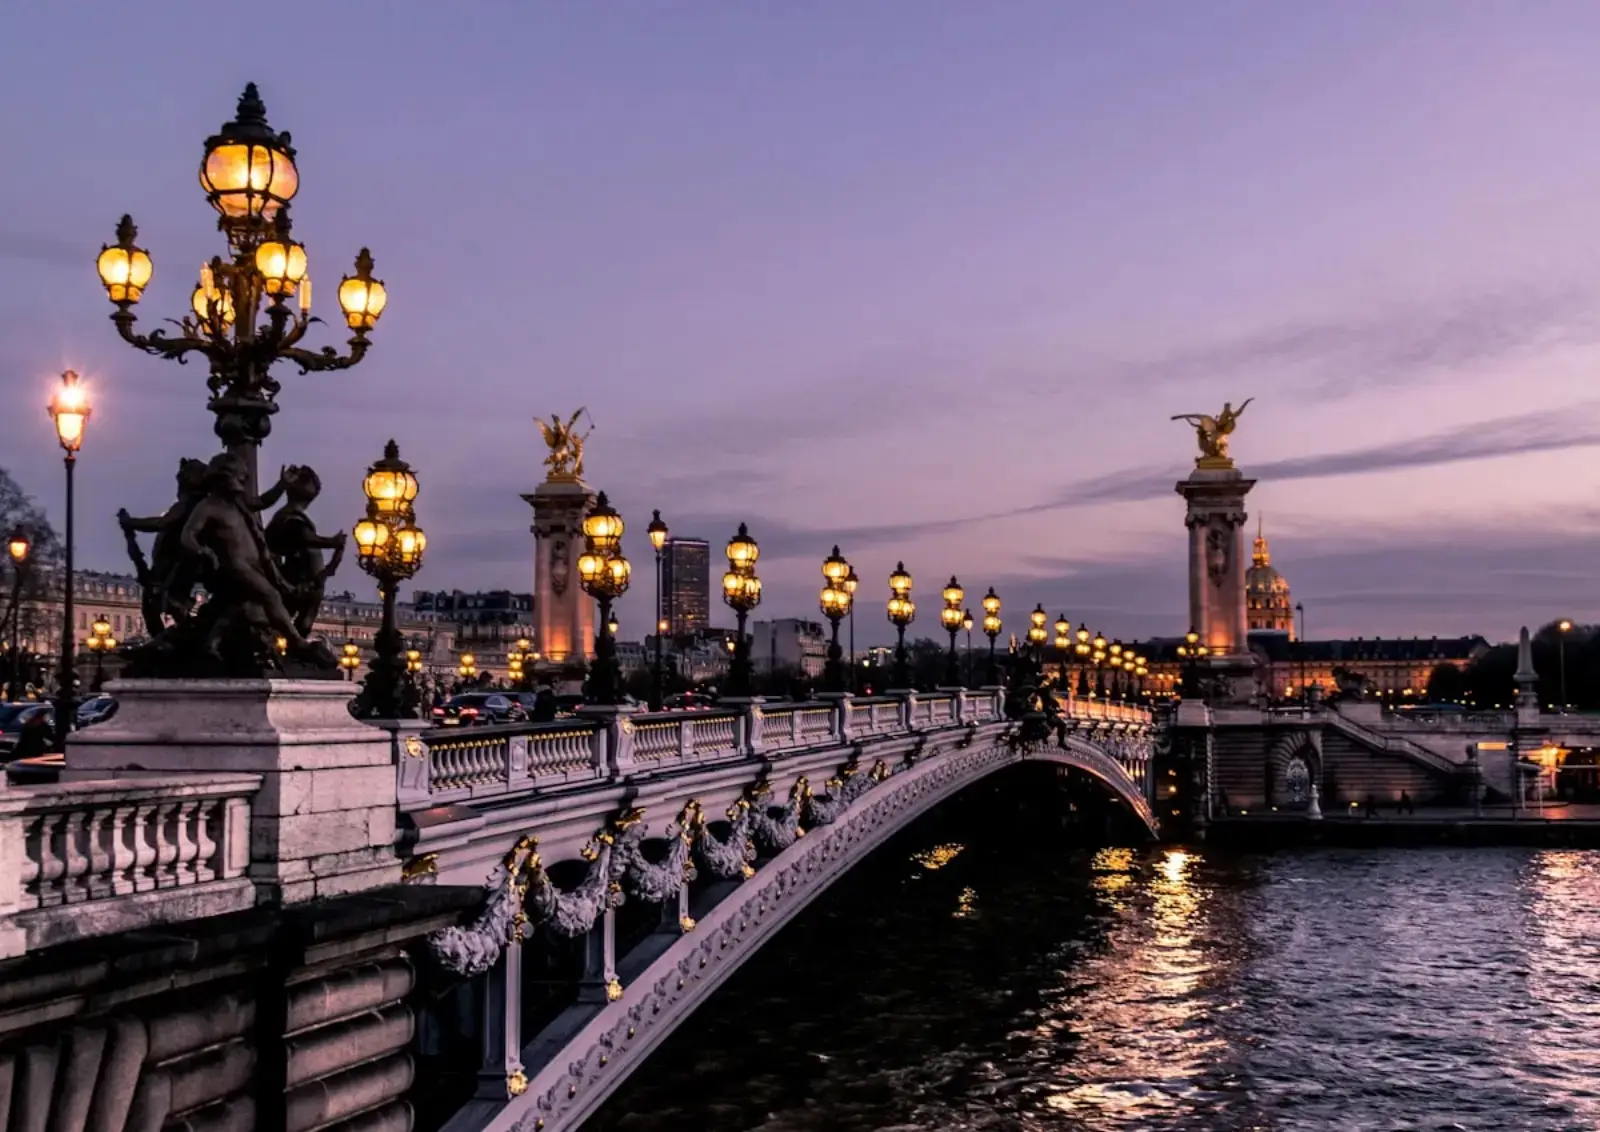
Paris Day 1 Arrival Playbook: CDG Airport Official Taxi vs. RER B, Navigo Easy, and Seine Sunset
Dodging illegal taxi touts at CDG for official flat-rate ranks, safe transit aboard the RER B, digital Navigo Easy ticketing, boulangerie ordering rituals, and golden hour along the Seine. A veteran field guide to your first 24 hours.
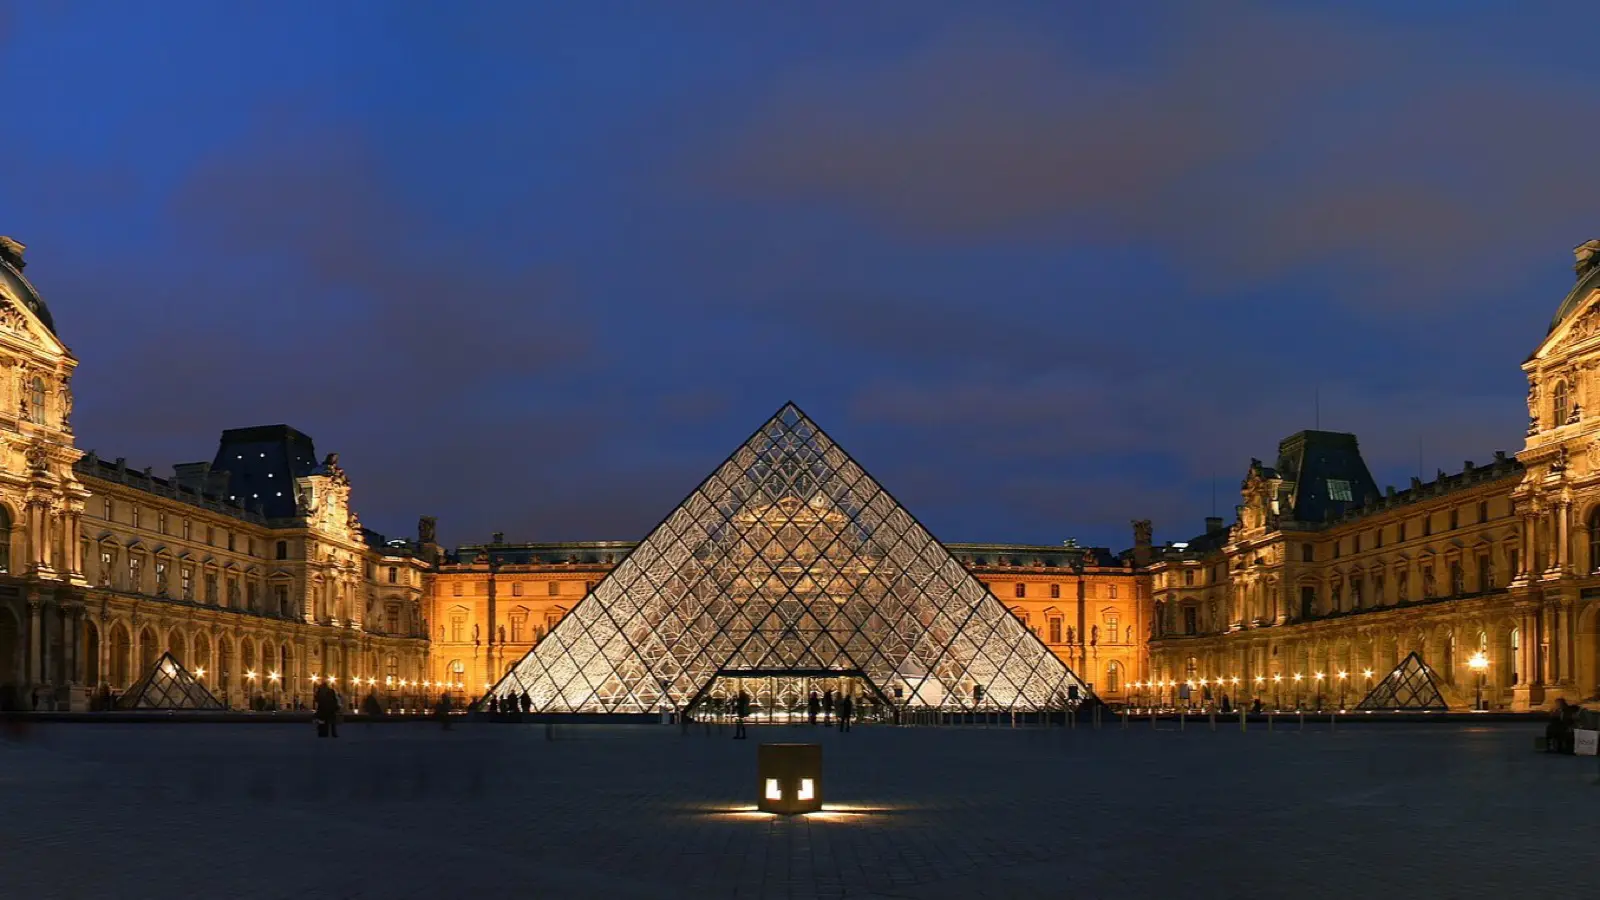
Paris Day 2 Playbook: Louvre Mona Lisa Sprint, Musee dOrsay, Latin Quarter, and Seine River Cruise
Experience an unhurried morning sprint to the Mona Lisa at the Louvre, stroll through the Tuileries to Musee dOrsay, browse Shakespeare and Company in the Latin Quarter, and glide past the sparkling Eiffel Tower on a twilight Seine River cruise.
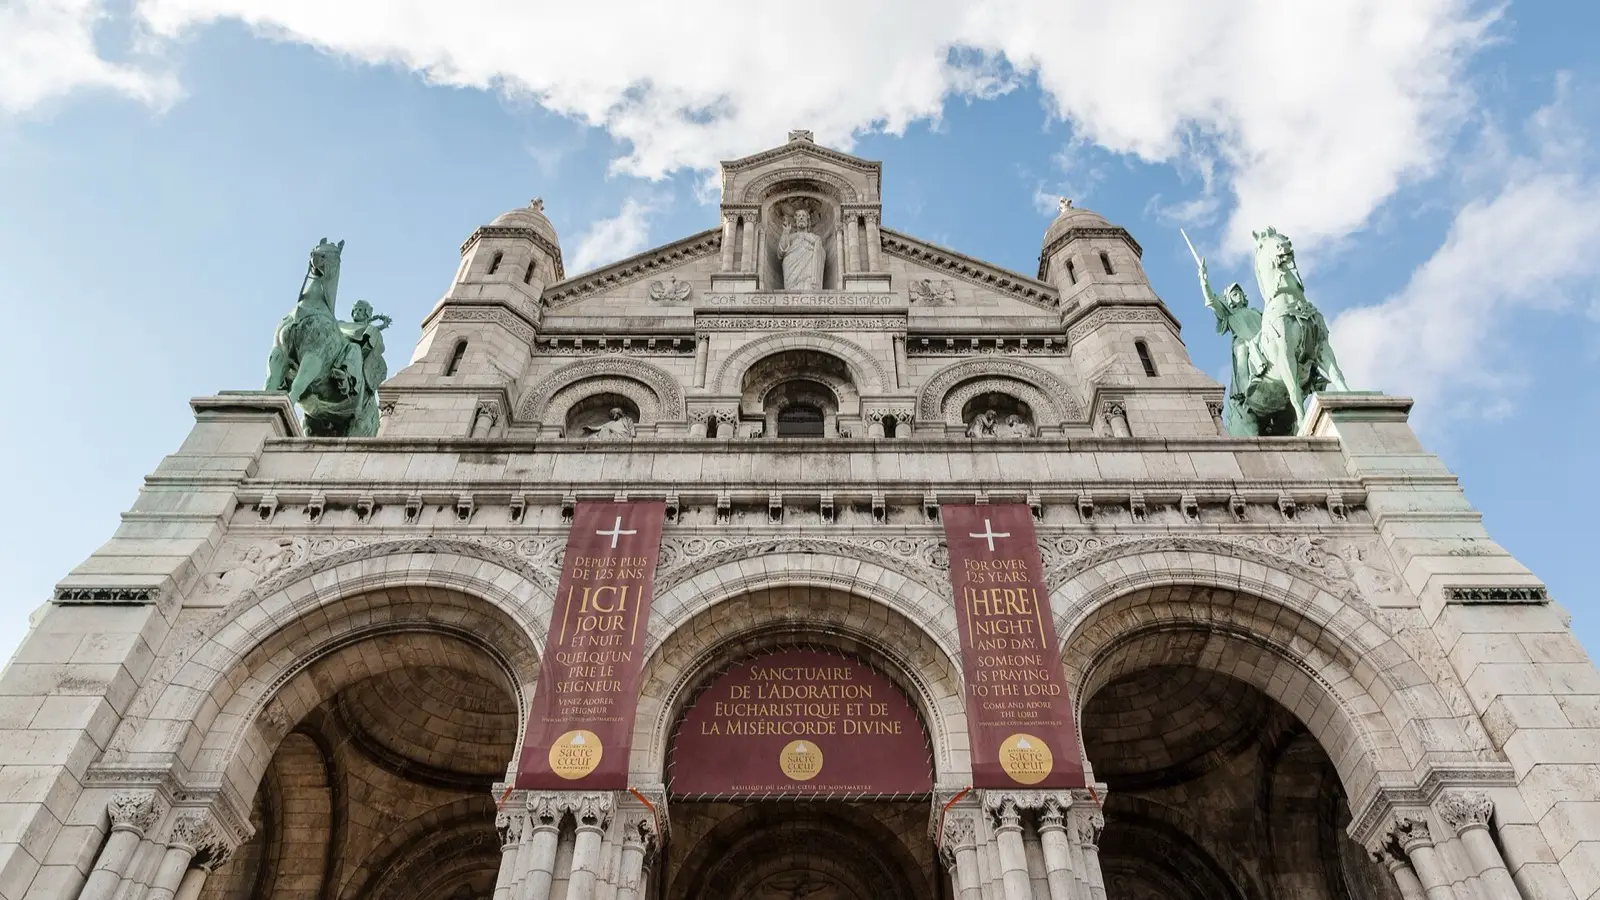
Paris Day 3 Finale: Montmartre Sacre-Coeur, Le Marais Boutiques, Galeries Lafayette, and CDG Departure
Ascend Montmartre for sweeping panoramas from Sacré-Cœur, hunt for vintage treasures and street falafel in Le Marais, enjoy free rooftop skyline views at Galeries Lafayette, and streamline departure via automated PABLO kiosks at Charles de Gaulle Airport.
Between Ubud Jungles and Uluwatu Cliffs: Securing Private Bali Pool Villas for Half the Peak Price
Smart 2+2 split stays across Ubud and Uluwatu, avoiding currency conversion markups, and getting real value from luxury pool estates.
Base in Osaka and Commute, or Wake Up on Kyoto's Kamo River?
Why splitting short Kansai trips across multiple hotels exhausts travelers, navigating Haruka vs. Rapi:t airport rail lines, and choosing between Umeda hubs and Gion alleys.
Osaka District Safety Guide: Kita (Umeda) vs Minami (Namba), Shin-Imamiya Realities, and Kushikatsu Etiquette
Behind Osaka's vibrant culinary spirit and affable banter lies a sharp geographic contrast between northern corporate efficiency and southern commercial chaos. Choosing between the labyrinth of Umeda and the neon crowds of Namba dictates your transit ease to Kyoto and Kansai Airport. Here is an unvarnished field guide to selecting strategically sound lodging and avoiding neighborhood missteps.
Osaka Day 1 Arrival Blueprint: Kansai Airport Rapi:t, Street Takoyaki, and Dotonbori Lights
From boarding the 34-minute Nankai Rapi:t train at Kansai Airport to navigating Namba Station, mastering takoyaki ordering and kushikatsu sauce rules, and taking a sunset Dotonbori canal cruise. A frictionless masterclass for your first 24 hours in Osaka.
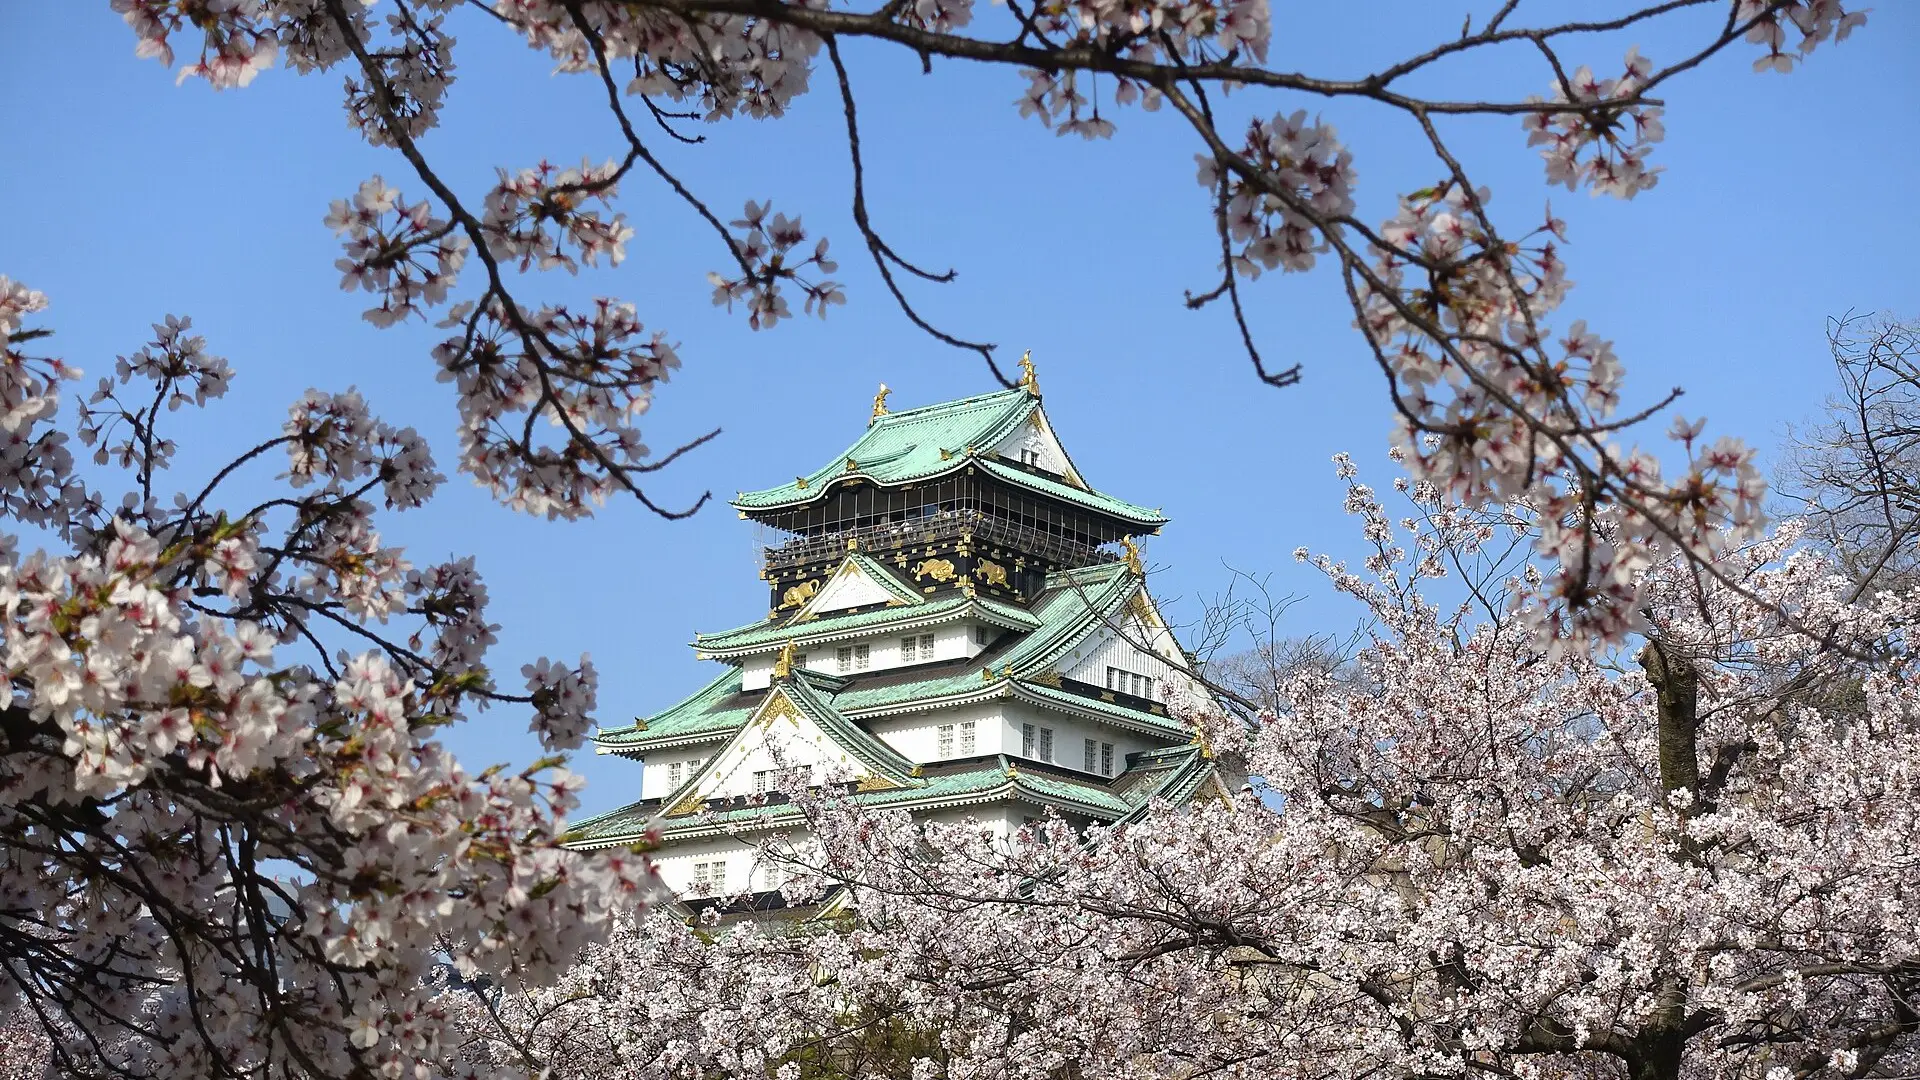
Osaka Day 2: Osaka Castle Morning, Umeda Sky Floating Garden, HEP FIVE, and Shinsekai Kushikatsu
Traversing past and future on Day 2 in Osaka: morning tranquility along the moats of Osaka Castle, futuristic open-air views from Umeda Sky Building, the iconic HEP FIVE red wheel, and dusk kushikatsu feasts in the neon shadow of Tsutenkaku.
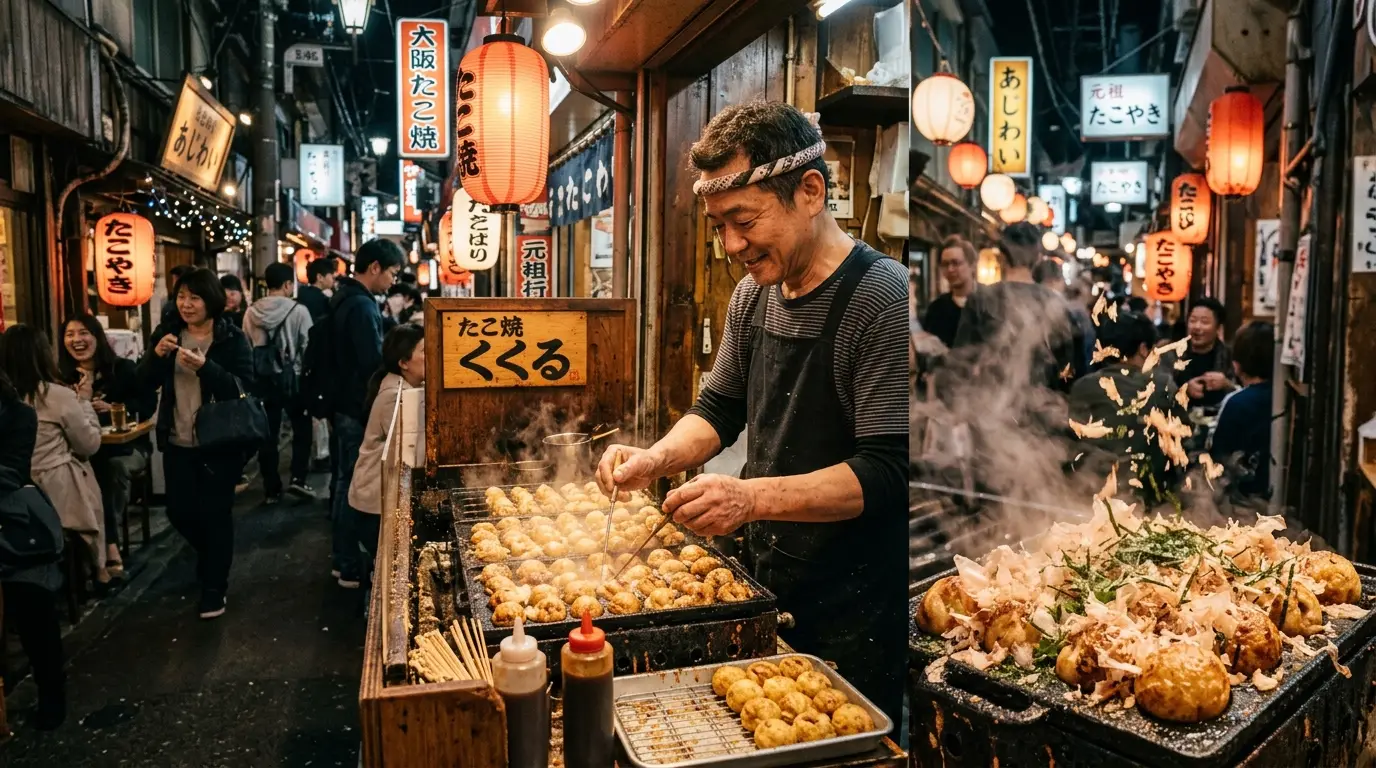
Osaka Day 3: Kuromon Market Feasts, Shinsaibashi Arcades, and Nankai Rapi:t Airport Departure
The definitive closing chapter to your Osaka journey: fresh sashimi feasts at Kuromon Market, vintage shopping along Amerikamura, covered retail in Shinsaibashi, and 34-minute express transit to Kansai Airport (KIX) aboard the iconic Nankai Rapi:t.
The 10-Second Global Hotel Rate Audit: Defeating Checkout Price Hikes and Currency Spreads
An investigative playbook uncovering why OTA final totals escalate, how desktop bank partner links consistently beat mobile app rates, and the exact local-currency checklist to stop hidden fees.
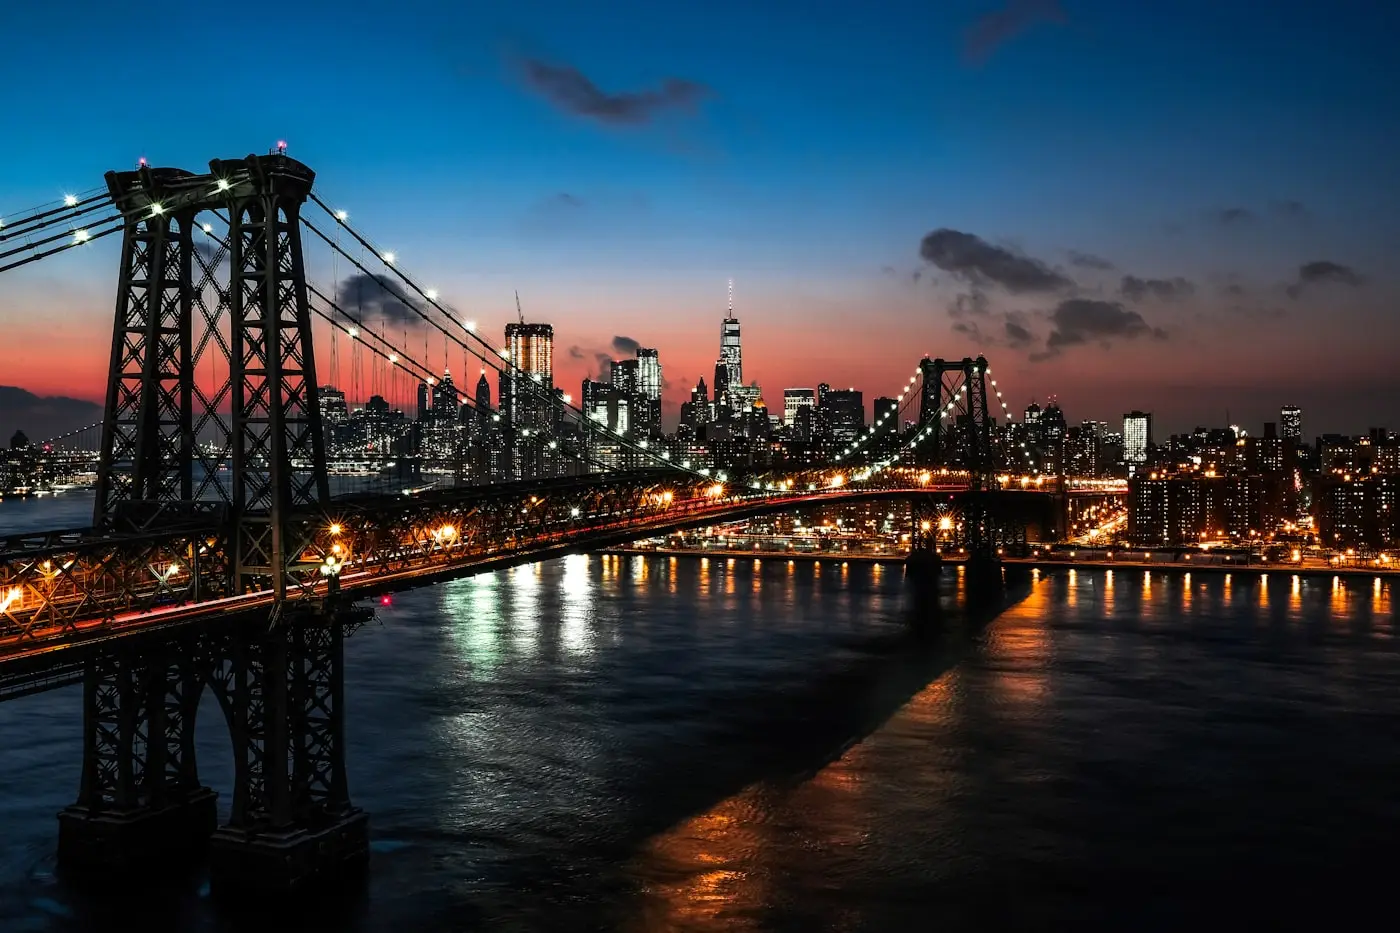
Outsmarting Manhattan's $50 Resort Fees: How to Claim Brooklyn & LIC Skyline Panoramas
An insider playbook on avoiding notorious $40-$65/night check-in amenity fees and leveraging transit-rich Long Island City and Brooklyn hubs for panoramic Manhattan skyline views.
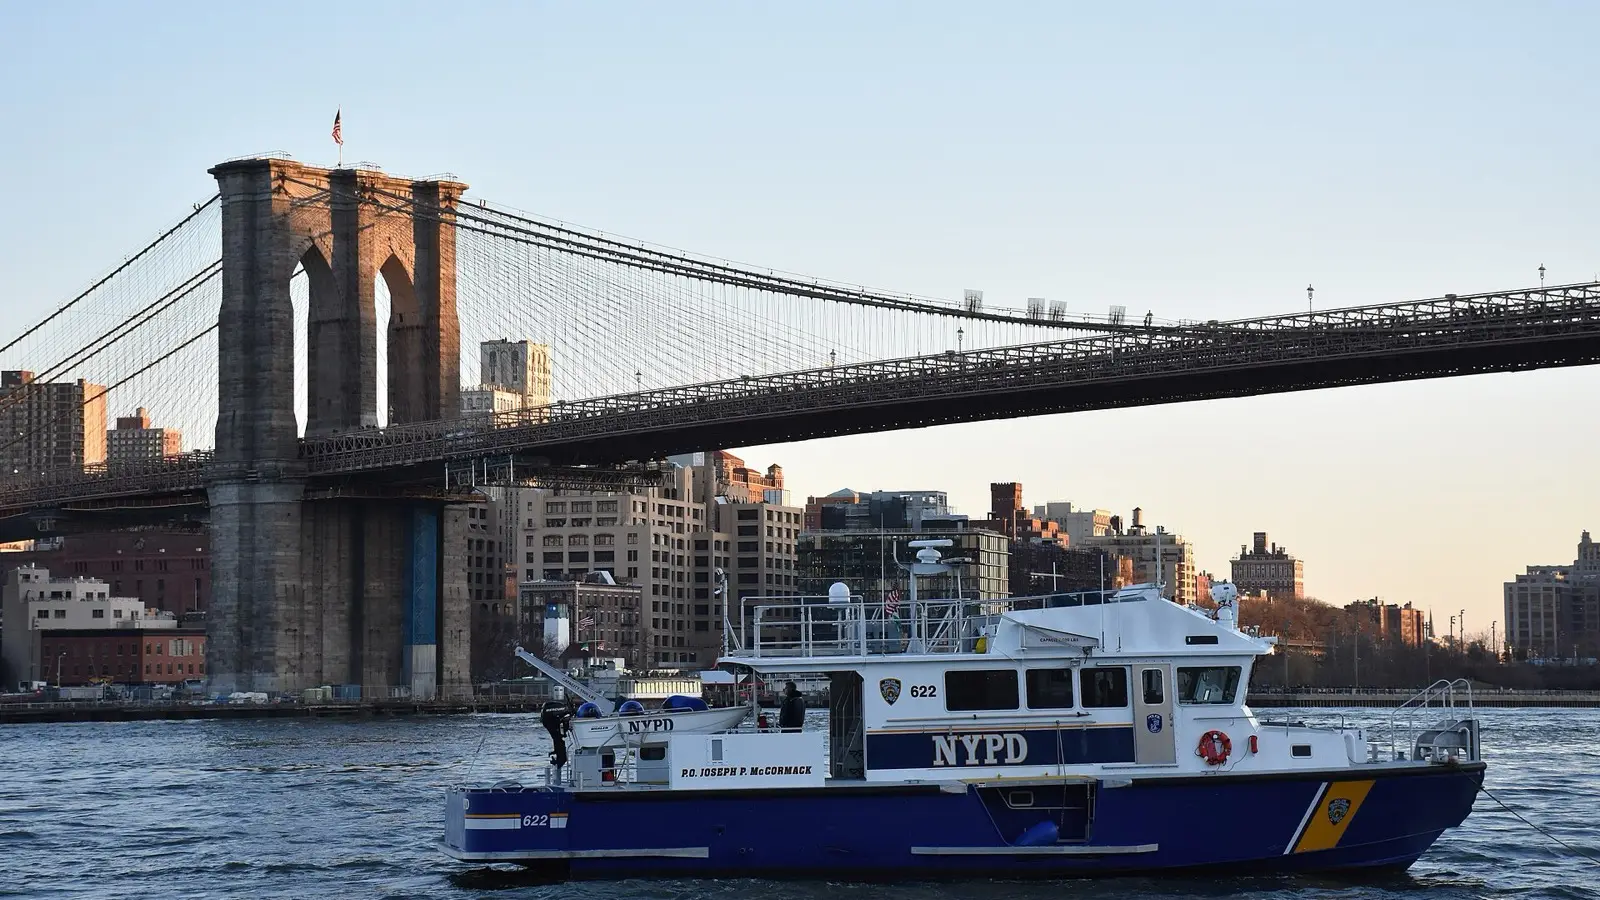
Escaping Manhattan's $350 Room Shock: The LIC & Brooklyn Blueprint, Dodging $50 Resort Fees, and OMNY Hacks
Amidst relentless inflation and soaring hotel rates, Manhattan room prices now routinely exceed $350 per night before taxes. Tacking on predatory $40 to $50 nightly 'Urban Destination Fees' can derail any travel budget. By shifting your lodging horizon just one subway stop across the East River to Long Island City (LIC) or Brooklyn's Williamsburg, you can slash accommodations costs by 45% while enjoying larger rooms and legendary skyline views. Here is the insider blueprint.
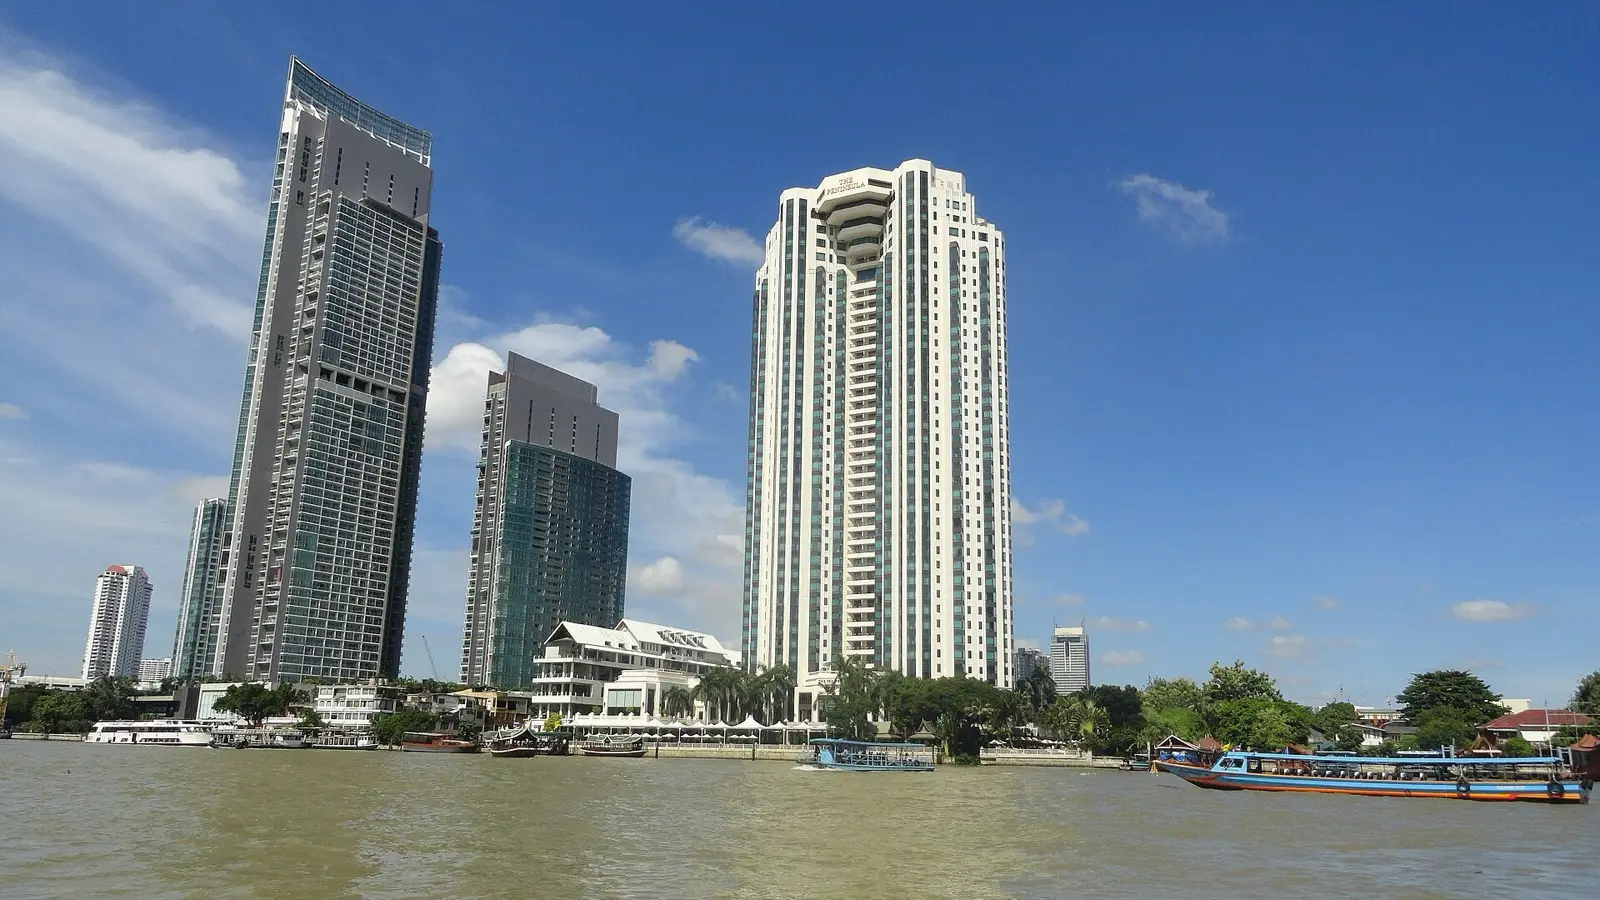
The Bangkok Luxury Hotel Playbook: Riverside Grandeur and Rooftop Pools Under $150
Comparing riverside and BTS shopping hubs, hacking executive club dining packages, and locking in pure THB settlement to dodge costly DCC card spreads.
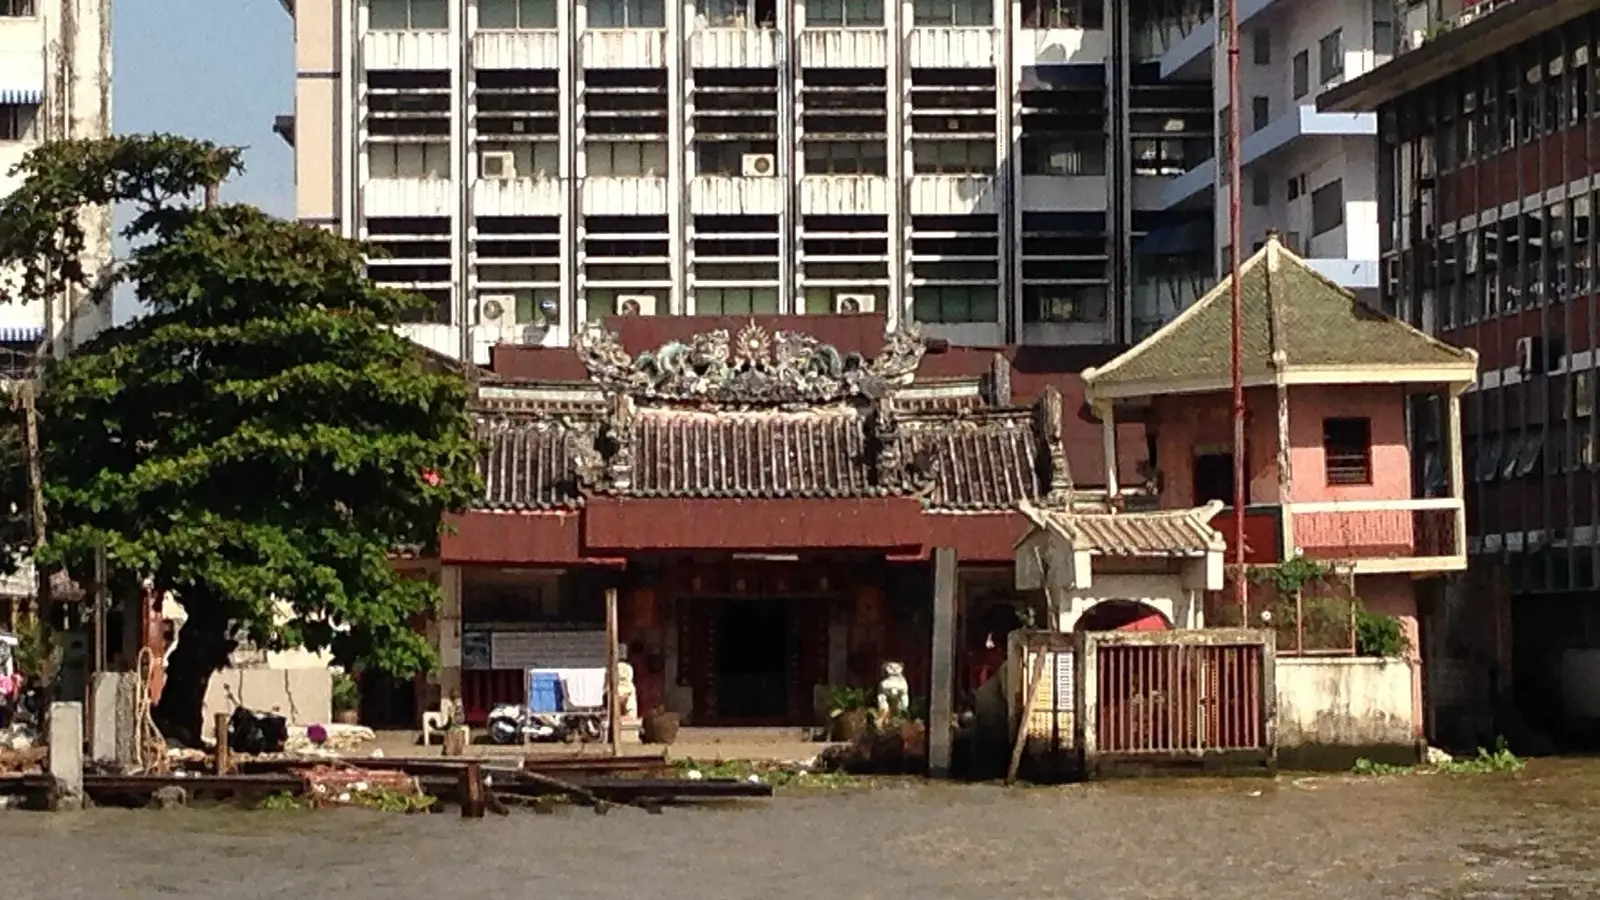
Bangkok Neighborhood Field Guide: Sukhumvit vs Silom vs Ari, Dodging Tuk-Tuk Scams, and Airport Taxi Realities
Beneath Bangkok's golden stupas and celebrated culinary vitality lies the world's most notorious gridlock and predatory transport rackets. Choosing where to drop your luggage dictates whether your holiday is spent absorbing local charm or trapped in exhaust-choked taxis. Here is an unvarnished field guide to selecting strategically sound lodging, evading classic tout operations, and mastering local transit.
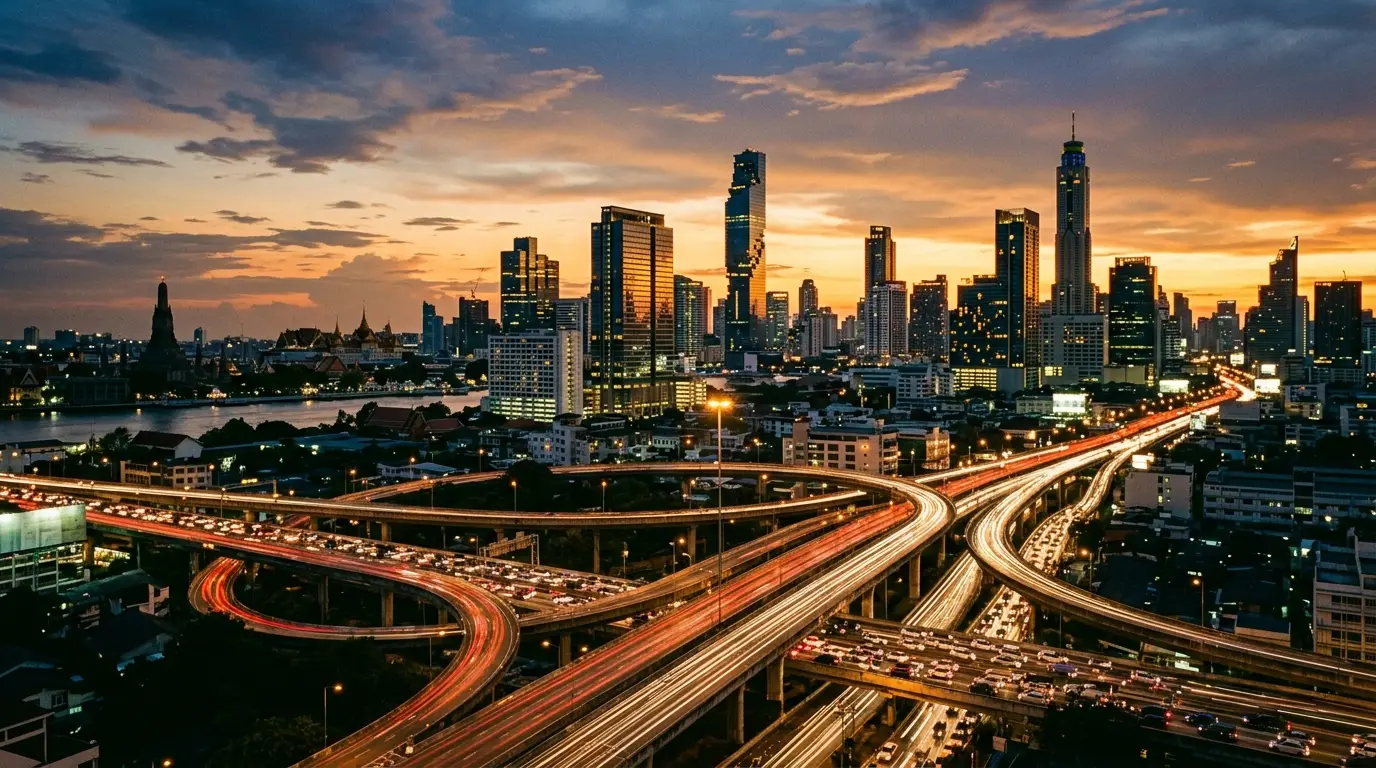
Bangkok Day 1 Survival Blueprint: Suvarnabhumi Airport Escape and the First 24 Hours
How to escape Suvarnabhumi Airport for 45 THB, order stress-free first meals without cilantro, catch golden hour at Lumphini Park, and stock up at 7-Eleven.
Bangkok Day 2: Chao Phraya River Cruise, Wat Arun, ICONSIAM, and Yaowarat Feasts
A sensory odyssey along the River of Kings on Day 2: breezy Chao Phraya express boats, the colossal 46-meter reclining gold Buddha at Wat Pho, shimmering porcelain spires of Wat Arun, air-conditioned street food delights inside ICONSIAM's SookSiam, and late-night wok-fried Michelin feasts in neon-lit Yaowarat.
Bangkok Day 3: Chatuchak Market, Siam Retail, Luxury Spas, and Suvarnabhumi Airport Departure
A flawless final 24 hours in Bangkok: treasure hunting across 15,000 stalls at Chatuchak Weekend Market, vacuum-sealed mango and tom yum snack hauls in Siam, soothing two-hour traditional herbal massages, and friction-free Airport Rail Link connections to Suvarnabhumi Airport (BKK).
Escaping Central London's Micro-Rooms: Strategic Stays in King's Cross and South Bank
Insider rules to avoid tiny Zone 1 micro-rooms, comparing King's Cross and South Bank value, and maximizing TfL daily fare caps with contactless payment.
London Neighborhood Stays Masterclass: Soho, Shoreditch, Kensington, and South Bank
London is not a monolithic sightseeing checklist, it is an archipelago of distinctive urban villages. From the electric late-night pub theater of Soho and the raw industrial design ateliers of Shoreditch to the refined Victorian museum promenades of South Kensington and the culinary riverside walks of South Bank, this comprehensive field guide unpacks where to stay, how to conquer the Elizabeth Line, and how to avoid the £7 Oyster card trap.
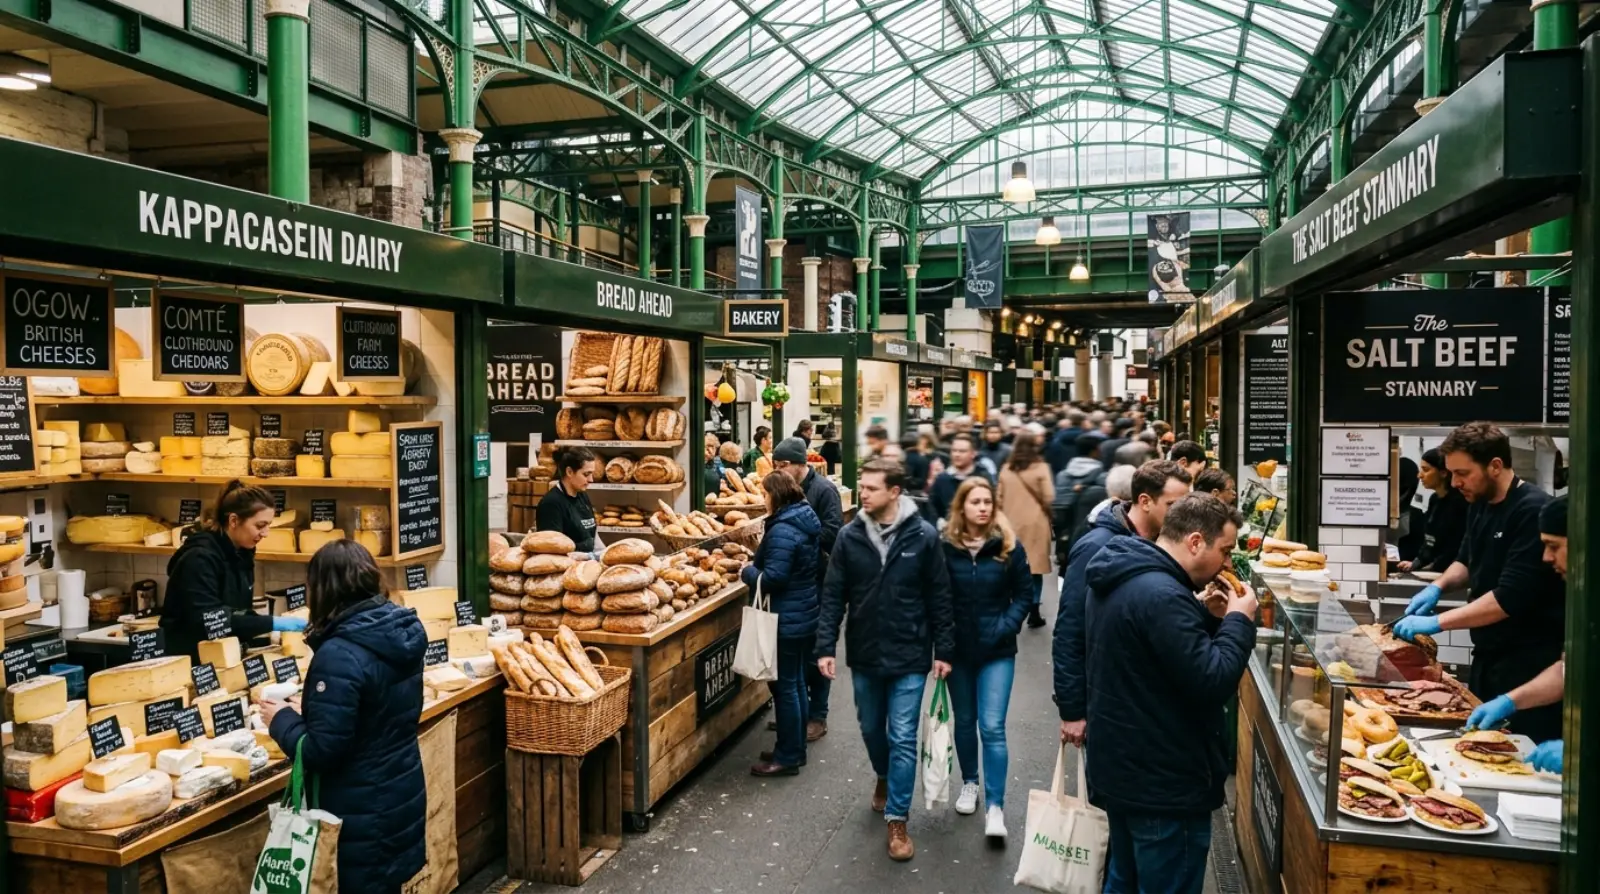
London Day 1 Blueprint: 15-Min Heathrow Express, Big Ben Chimes, and Borough Market Feasts
Mastering the 15-minute Heathrow Express sprint to Paddington, unlocking TfL contactless daily fare capping, admiring Big Ben chimes, strolling along the vibrant Thames South Bank, and feasting on artisan street fare at Borough Market: here is your definitive first 24 hours in London.
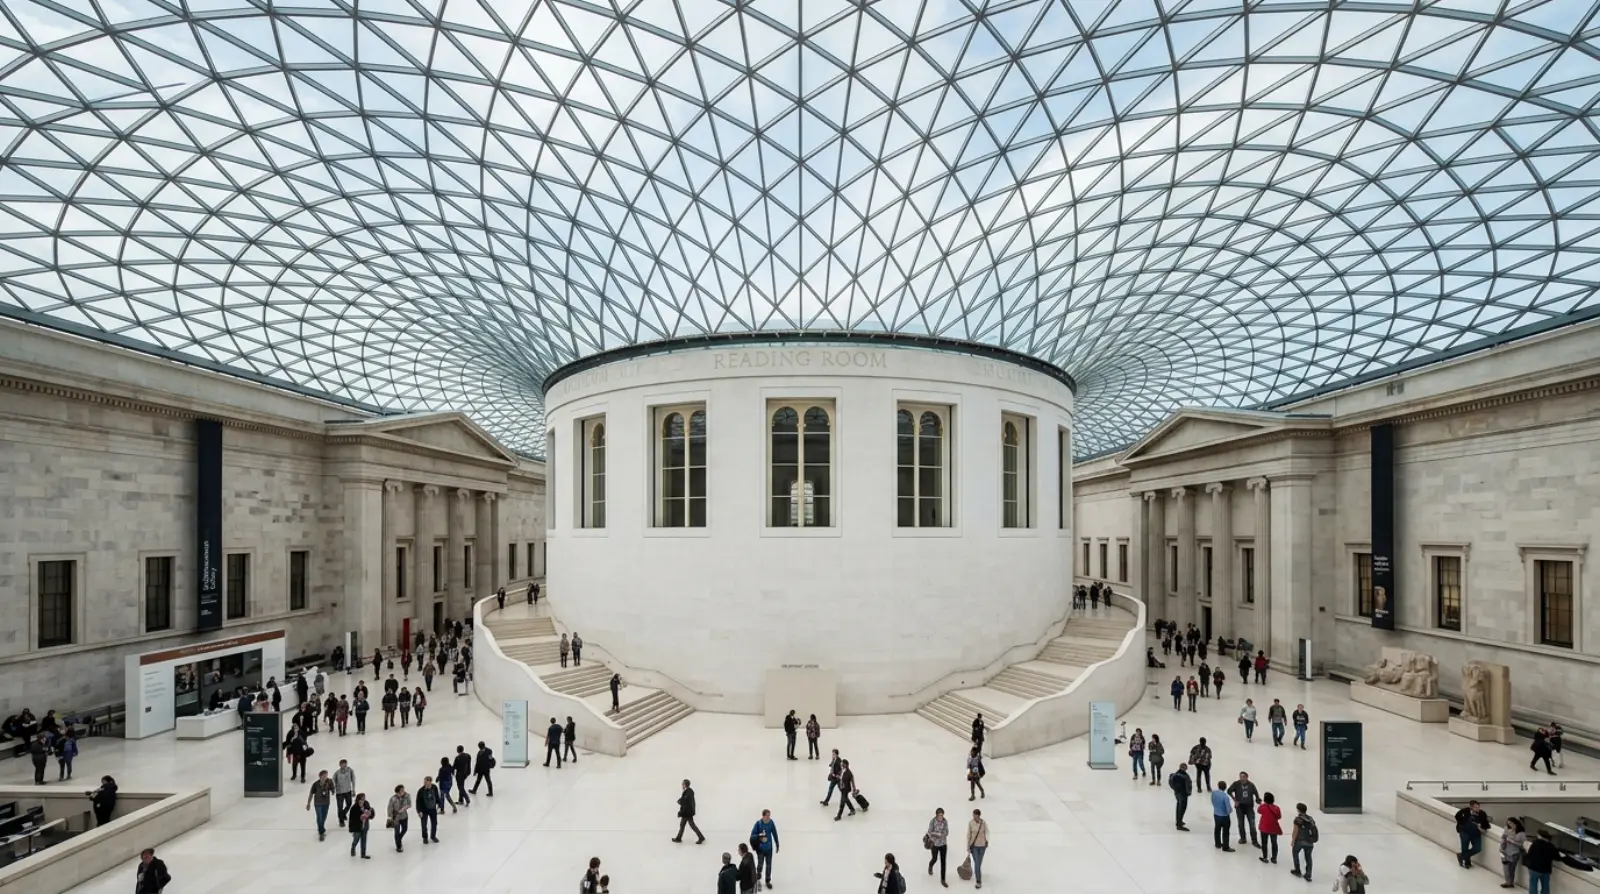
London Day 2 Cultural Blueprint: British Museum Treasures, Covent Garden Buskers, and West End Nights
Standing beneath the breathtaking glass canopy of the British Museum's Great Court, savoring Monmouth filter coffee amid the operatic buskers of Covent Garden, exploring independent fashion across Seven Dials and Soho, and witnessing world-class West End musical theatre before midnight Chinatown dim sum: here is your essential London Day 2.
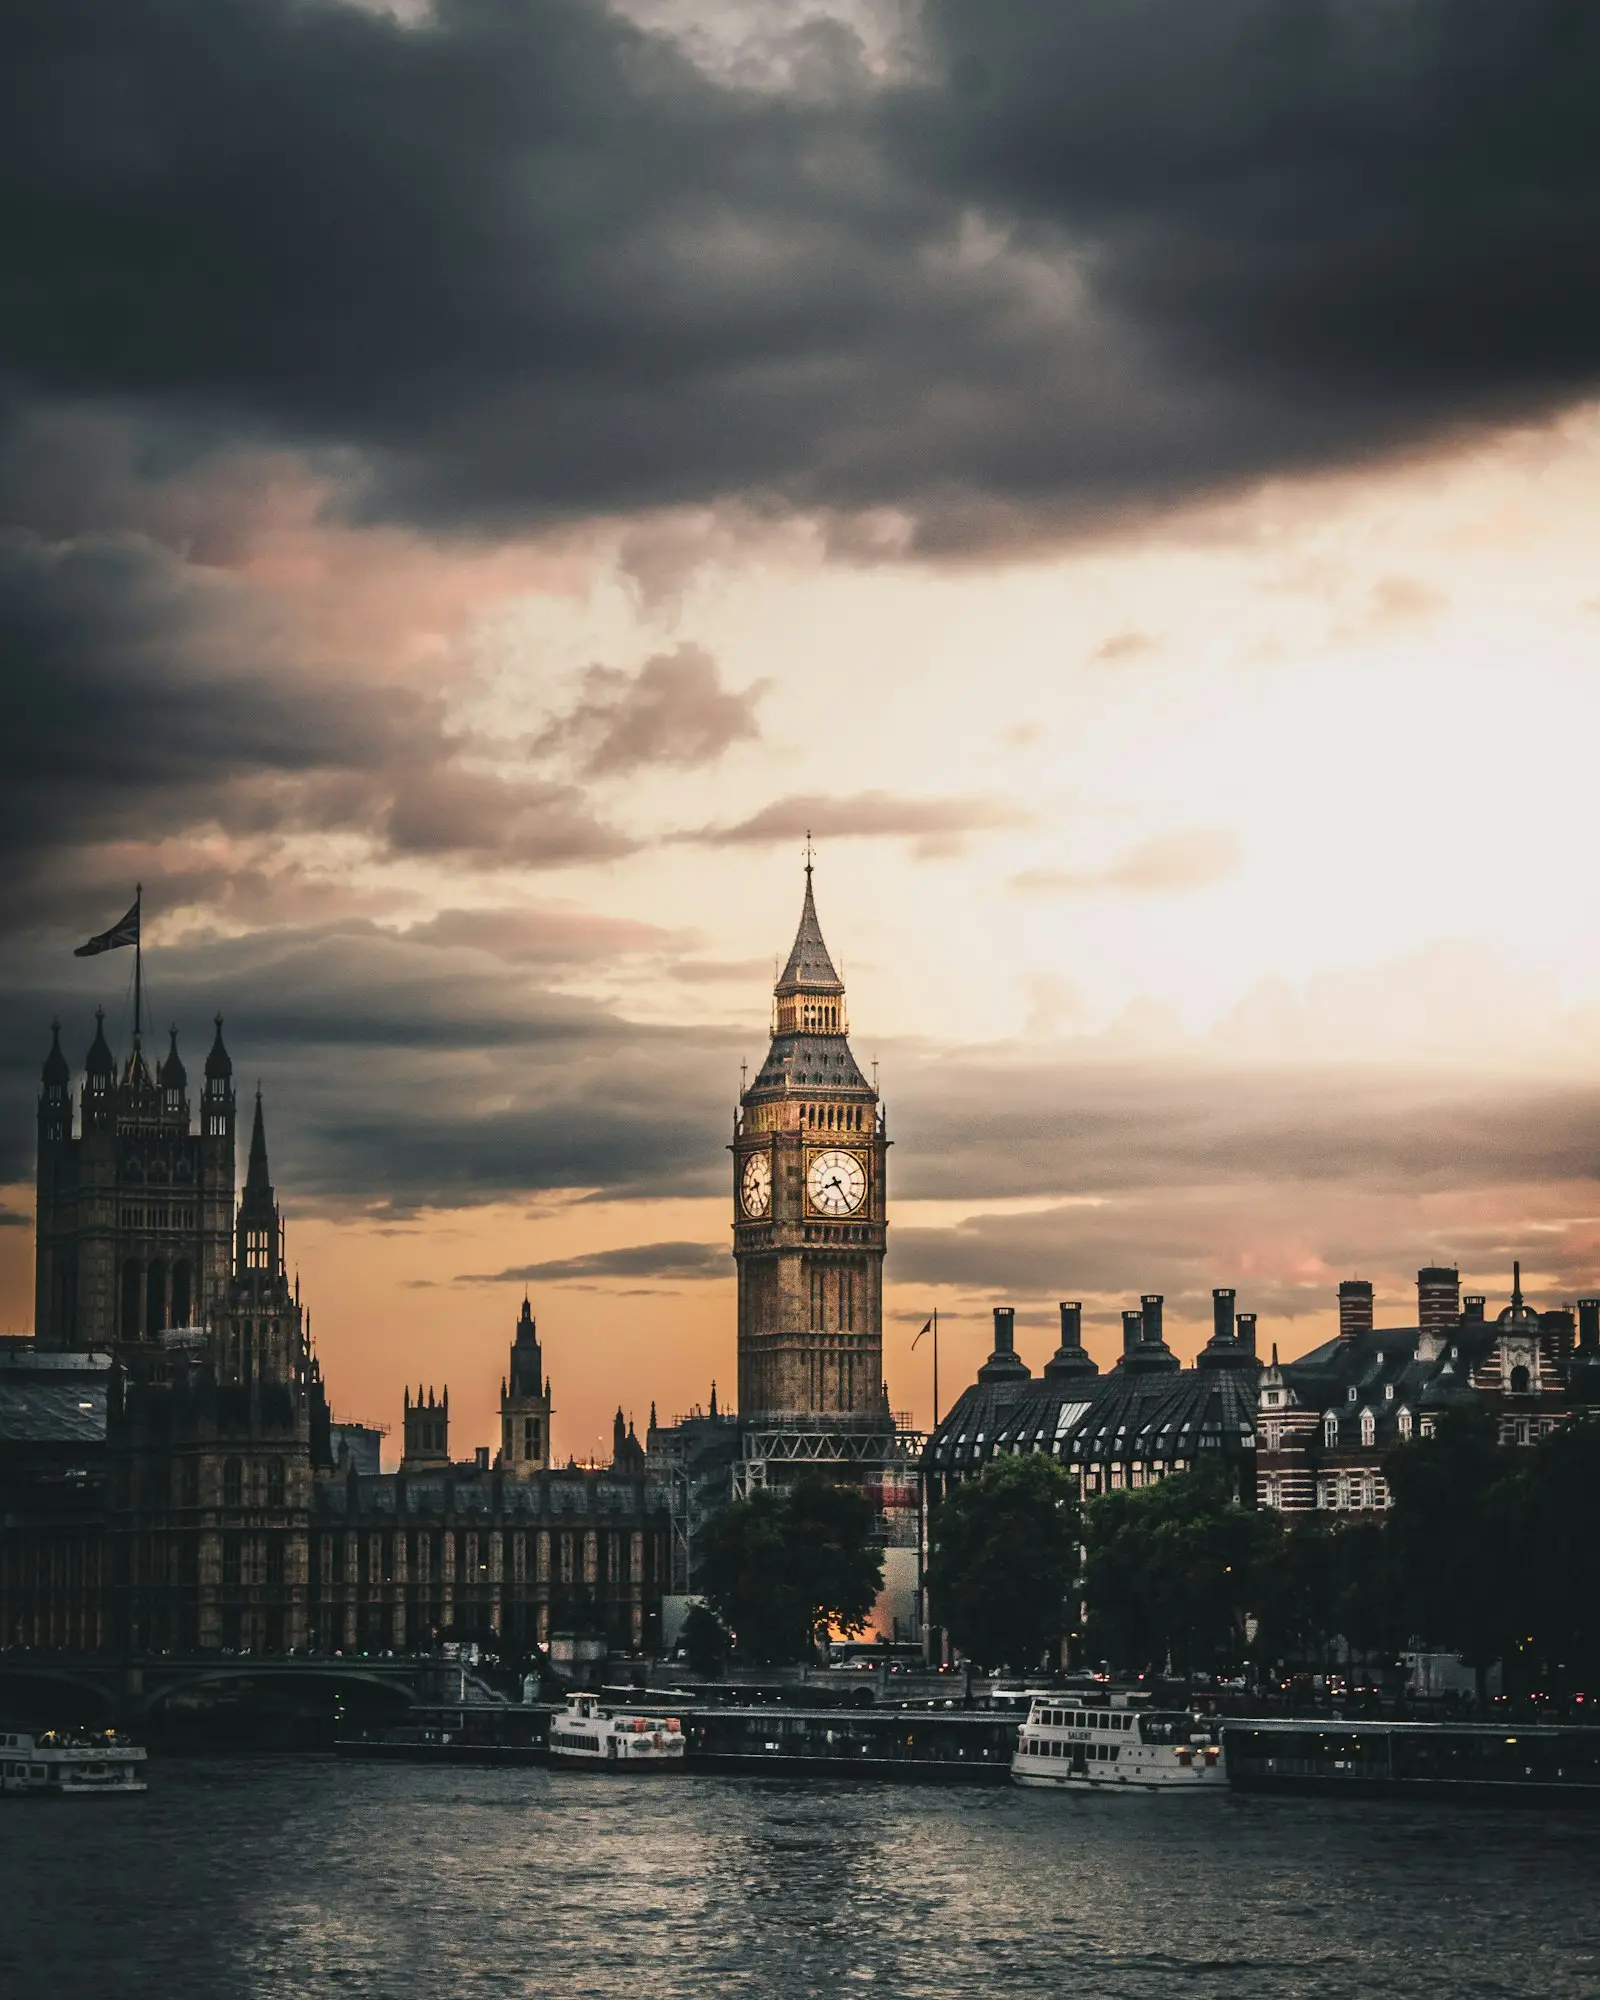
London Day 3 Heritage Blueprint: Tower Crown Jewels, Tower Bridge Glass Walk, and Shoreditch Murals
Witnessing the 530-carat Cullinan diamond in the Crown Jewels at the Tower of London, stepping onto the glass floor 42 meters above the Thames on Tower Bridge, diving into the vintage markets and street art of Shoreditch, and enjoying Hyde Park afternoon tea before an effortless Elizabeth Line airport departure: your definitive London finale.
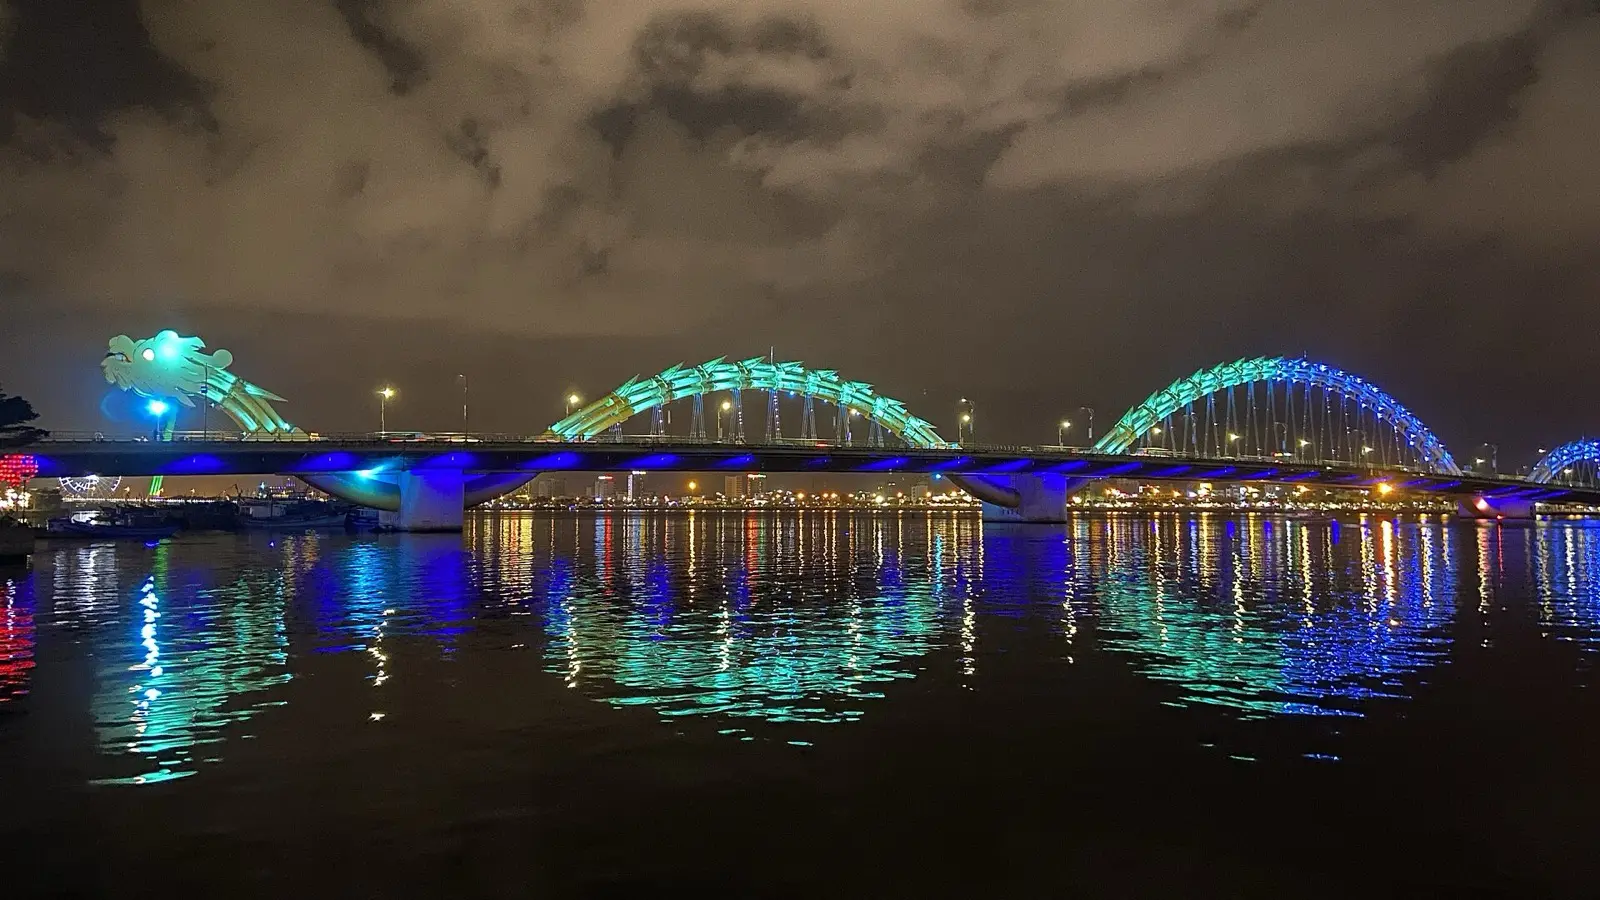
Danang and Hoi An Luxury Beachfronts: Securing 30% Off Private Pool Villas
A strategic breakdown of My Khe, Non Nuoc, and Hoi An lodging hubs, locking in 60-day early-bird villa rates, and mastering VND zero-markup payments.
Da Nang & Hoi An Dual-Stay Masterclass: Oceanfront Towers, Lantern Alleys, and Grab Logistics
Thirty kilometers separate Da Nang's gleaming beachfront skyline from the timeless, lantern-lit yellow shophouses of Hoi An Ancient Town. Rather than suffering through exhausting day-trip tour buses, this comprehensive field playbook shows you how to execute a seamless dual-stay itinerary, outsmart street boat touts, and master local Grab transport.
Da Nang & Hoi An Transit & Neighborhood Playbook: Airport Scams, Grab Hacks, and Coastal Bases
How to dodge airport taxi traps with official Grab bays in Da Nang, analyze ride-hailing economics, and choose the right stay between My Khe Beach, downtown, and Hoi An.
Da Nang Day 1 Arrival Playbook: DAD Airport Grab Escape, My Khe Bánh Mì, and Dragon Bridge Sunset
From escaping Da Nang airport crowds via official Grab bays and swapping cash near Han Market, to stress-free bánh mì ordering and Dragon Bridge sunsets. A veteran playbook for your first 24 hours.
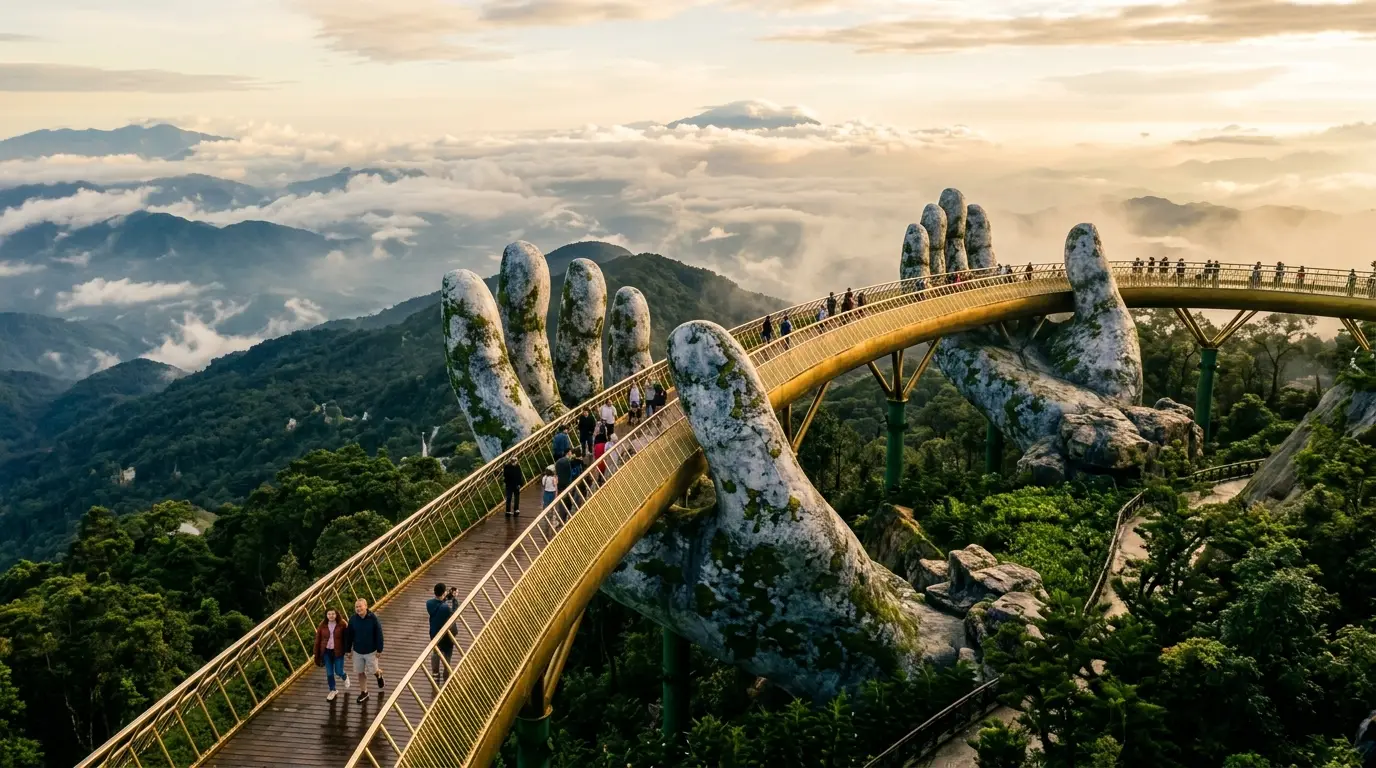
Danang Day 2: Ba Na Hills Golden Bridge, Marble Mountain Caves, and Dragon Bridge Fire Spectacle
An exhilarating day connecting Danang's mountain heights, coastal wonders, and illuminated riverbanks: ascend through morning clouds aboard world-record cable cars to the iconic Golden Bridge at Sun World Ba Na Hills, explore mystical cavern shrines bathed in natural skylight inside Marble Mountains, feast on fresh grilled seafood along My Khe Beach, and cap off the night witnessing the fire-breathing Dragon Bridge over the Han River.
Danang Day 3: Son Tra Lady Buddha, Han Market Souvenirs, Pre-Flight Spa, and Airport Departure
A sublime finale to your central Vietnam holiday: morning vistas beneath the 67-meter Lady Buddha on the Son Tra Peninsula, lively bargaining for artisan coffee and roasted cashews inside Han Market, coconut basket boat rides, rejuvenating pre-flight hot-stone spa rituals, followed by a swift 15-minute Grab ride to Danang International Airport for effortless departures.
Navigating Eternal Rome: Termini Transit Efficiency vs. Centro Storico Romance and ZTL Traps
Comparing Termini station transit convenience with historic Pantheon and Navona luxury, plus critical advice on Italy's mandatory city tax.
Rome District Safety Guide: Monti vs Trastevere vs Prati, Navigating Termini, and Evading €7.50 City Tax Traps
Beneath the eternal splendor of ancient forums and cobbled piazzas lies an aggressive pickpocket network and some of Europe's steepest municipal tourist surcharges. Escaping the chaotic fringes of Termini Station requires street-by-street local awareness. Here is an unvarnished investigative field guide to booking genuinely secure Roman lodging, evading transit scams, and navigating the Eternal City with seasoned confidence.
Rome Day 1 Blueprint: 32-Minute Airport Transit, Monti Trattorias, and Colosseum Sunset Strolls
From touching down at FCO Airport to breezing into Roma Termini in 32 minutes aboard the Leonardo Express, here is how to navigate ancient cobblestones with heavy luggage. Savor an authentic Cacio e Pepe in Rione Monti, master Italian espresso etiquette, and watch the sun melt over the Colosseum arches on your first evening.
The Fukuoka Insider Booking Guide: 5 Rules for 4-Star Stays in Tenjin & Hakata
A complete guide comparing Hakata Station vs Tenjin hotel zones, avoiding DCC currency markup with JPY payments, and handling local accommodation taxes.
Fukuoka Transit & Neighborhood Blueprint: Airport Bus Secrets, Metro Hacks, and Hakata vs Tenjin
How to bypass crowded airport terminal shuttles with direct buses in Fukuoka, master contactless subway gates, and pick the best base between Hakata and Tenjin.
Fukuoka Day 1 Arrival Playbook: Two-Stop Airport Subway Escape, Hakata Ramen, and Nakasu Yatai
From reaching Hakata Station in five subway minutes to securing station lockers, ordering authentic tonkotsu ramen with custom firmness, and navigating Nakasu yatai etiquette. A veteran guide to your first 24 hours.
Fukuoka Day 2: Dazaifu Tenmangu Morning, Ohori Park Tranquility, Tenjin Arcades, and Motsunabe Feasts
Day 2 immerses you in Fukuoka's finest cultural textures: riding the Nishitetsu express to ancient Dazaifu Tenmangu for crispy plum rice cakes, unwinding along the weeping willows of Ohori Park, exploring Tenjin Underground Mall's vaulted corridors, and dining over bubbling motsunabe beef offal hotpots.
Fukuoka Day 3: Kushida Shrine, Canal City, Hakata Station Sweets, and 5-Minute Airport Access
The ultimate finale for your Fukuoka journey: morning serenity at eighth-century Kushida Shrine, dynamic musical water shows at Canal City Hakata, souvenir hauls at Hakata Hankyu, and world-class subway airport transit clocking in at just five minutes flat.
Sunlit Barcelona Strategy: Eixample Boutique Sanctuaries and Defeating Municipal Tourist Taxes
Comparing Eixample, the Gothic Quarter, and coastal Poblenou, deconstructing local tourist taxes, and managing strict Gaudí ticketing rules.
Barcelona Neighborhood Safety Guide: Eixample vs Gothic Quarter, Evading Paella Traps, and Direct Gaudi Bookings
Behind Barcelona's Mediterranean sunshine and Gaudi masterworks lies Europe's most notorious pickpocket ecosystem and rapidly escalating tourist surcharges. Escaping the noise and petty crime of the Ciutat Vella requires knowing exactly where to cross the street. Here is an unvarnished insider guide to securing safe, value-driven Catalan lodging and navigating the city with seasoned poise.
Barcelona Day 1 Blueprint: 35-Minute Aerobus Express, El Born Tapas Crawls, and Gothic Sunset Strolls
From stepping off the plane at El Prat Airport to reaching Placa de Catalunya in 35 minutes aboard the blue Aerobus, here is how to dodge tourist traps and settle into El Born. Savor toothpick-tallied pintxos, crack the code of weekday Menu del Dia bargains, and wander ancient Gothic alleys as golden hour floods the Mediterranean coast.
Navigating Chongqing 8D Cyberpunk Labyrinth and Scoring $50 Riverfront Suites
A field guide to mastering vertical geography, comparing Jiefangbei and Nanbin Road riverfront bases, eliminating transaction fees via Alipay, and navigating 3D hills with Didi ride-hailing.
Friday Night in Shanghai: 100 Minutes to the Glowing Bund Skyline
Comparing Bund riverview suites vs. Wukang Road heritage villas, evading checkout Yajin security deposit card holds, and mobile transit hacks.
How to Avoid Dragging Frozen Suitcases Through Minus-Ten Sapporo
An insider guide to heated underground walkways, securing 7:30 AM Biei snow tour departures at Sapporo Station, and evading New Chitose airport blizzard traps.
Sapporo & Otaru Snow Country Masterclass: Susukino Gastronomy, Canal Gas Lamps, and Onsen Ryokans
When winter descends upon Hokkaido, Sapporo transforms into a silent, snow-carpeted wonderland. Beneath the freezing surface lies an astonishingly warm culture: bubbling cauldrons of soup curry in Susukino, century-old stone canal warehouses in Otaru, and secluded steaming rotenburo hot springs in Jozankei. Here is the definitive field guide to mastering Hokkaido's premier winter duo with insider precision.
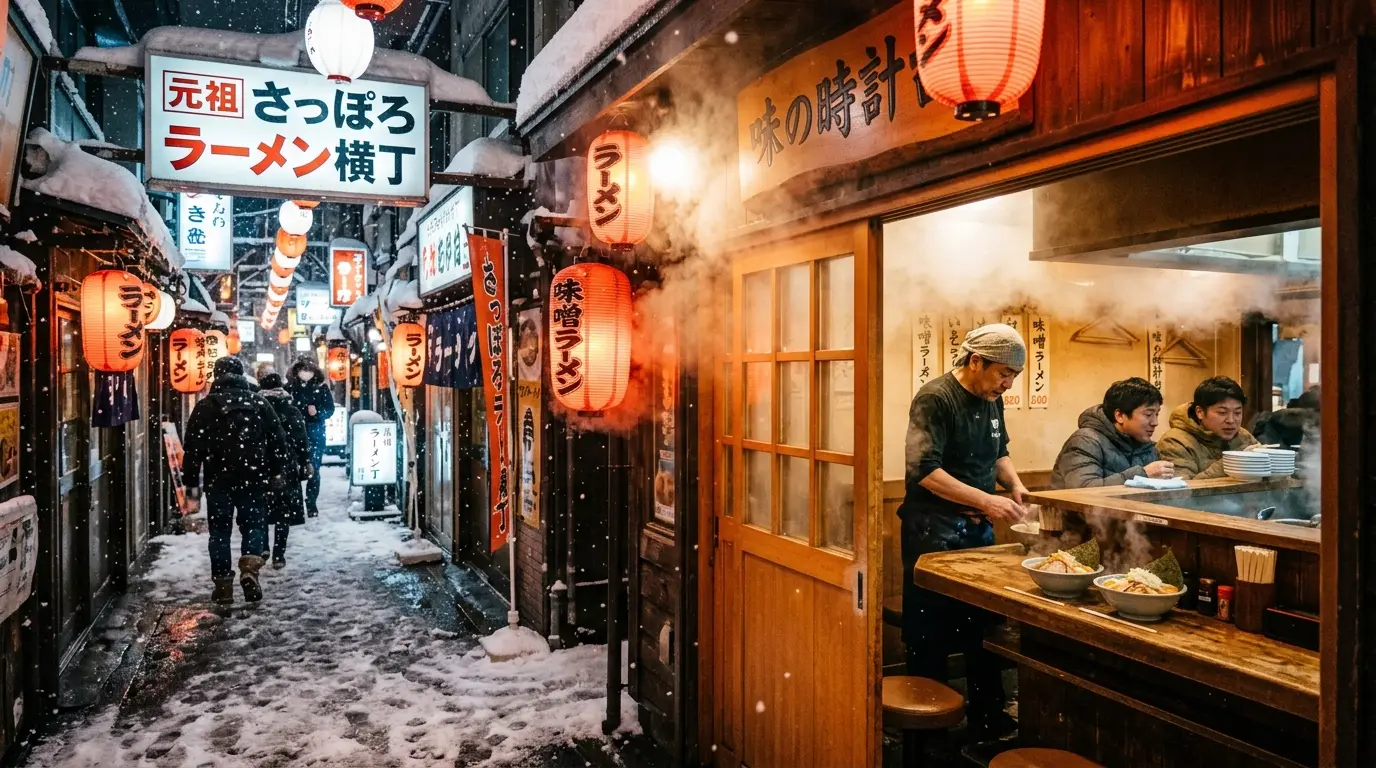
Sapporo Day 1 Snowfall Arrival: 37-Min Rapid Airport, Ganso Miso Ramen, and Midnight Shime Parfait
The essential first 24 hours in Hokkaido's snow capital: mastering the 37-minute JR Rapid Airport train, walking the heated Chi-Ka-Ho underground labyrinth, watching the twilight snowfall from Odori Park, devouring rich butter-corn ramen in historic Susukino, and tasting an architectural midnight shime parfait.
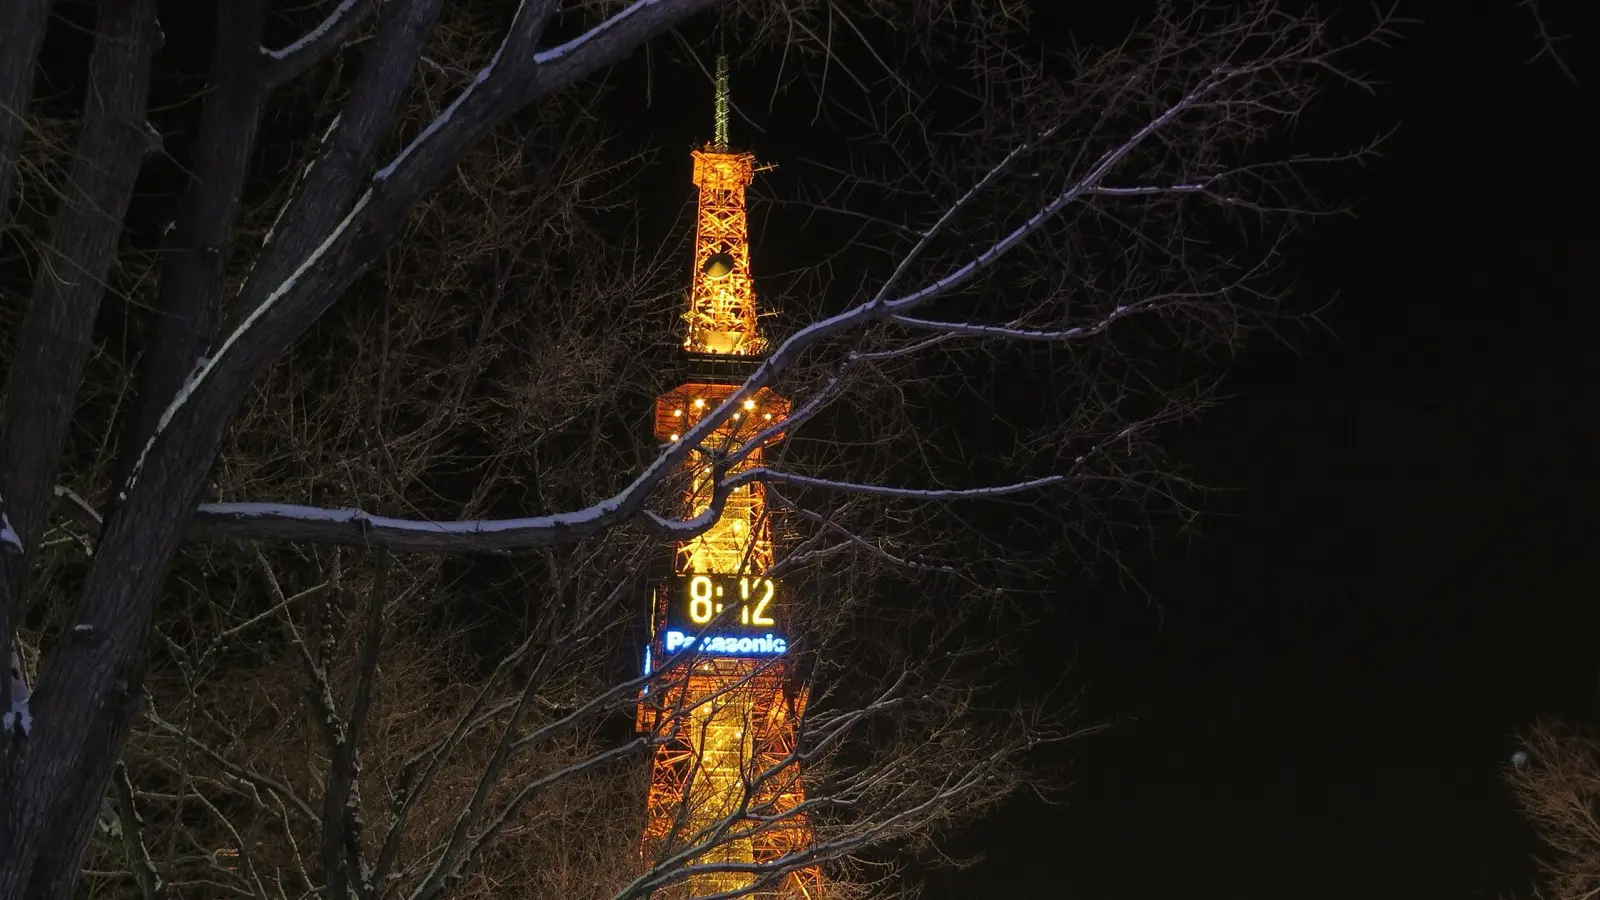
Sapporo Day 2 Epicurean Heights: Beer Museum Genghis Khan, Hokkaido Shrine, and Mount Moiwa Panoramas
Immerse yourself in Hokkaido's premier sights: touring the historic 1890 red-brick Sapporo Beer Museum with a freshly poured three-glass flight, savoring sizzling Genghis Khan grilled lamb in a soaring Bavarian-style hall, walking the snow-clad forest paths of Hokkaido Shrine, and ascending Mount Moiwa for one of Japan's Top Three Night Views.
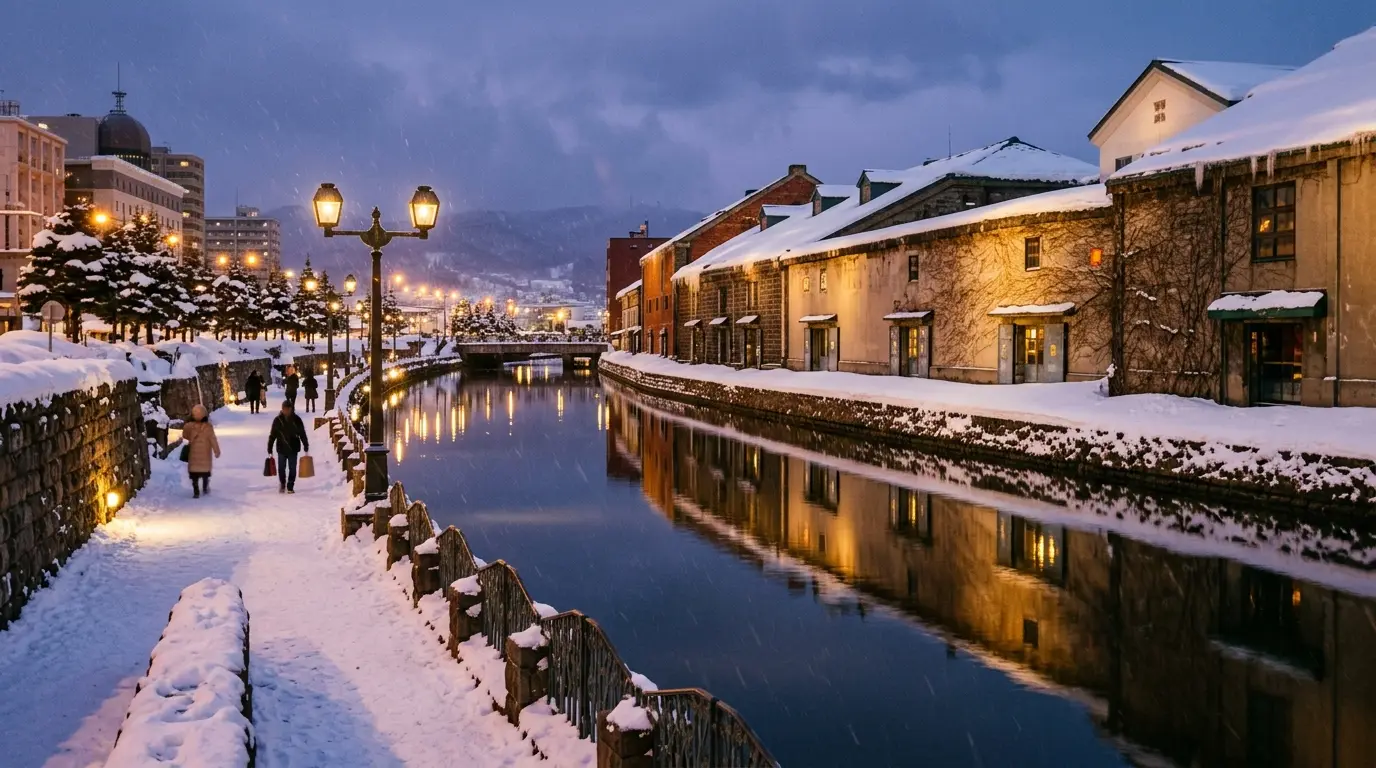
Sapporo Day 3 Otaru Romantic Finale: Canal Gas Lamps, LeTAO Double Fromage, and Airport Confections
The definitive grand finale: riding the coastal JR Rapid train along snow-covered Ishikari Bay to Otaru, admiring century-old stone canal warehouses and gas lamps, savoring freshly made double fromage cheesecake at LeTAO's flagship, indulging in mountain-high sea urchin kaisendon at Sankaku Market, and sweeping through New Chitose Airport's legendary confectionery halls.
Dodging Taipei Windowless Rooms: The Weekend Red-Eye Playbook
Comparing Ximending boutiques against Taipei Main Station hubs, stacking Taiwan 5,000 TWD Lucky Land draw at front desks, and dodging credit card DCC surcharges.
Taipei Beitou Thermal Springs & Dadaocheng Tea Haven Playbook
From soothing natural sulfur hot springs in Beitou via MRT Red Line to century-old tea salons in Dadaocheng and Ningxia culinary night markets, an authentic 4-day Taipei itinerary.
Taipei District Field Guide: Ximending vs Zhongshan vs Daan, Wanhua Safety, and Dehumidifier Realities
Behind Taipei's warm hospitality and celebrated night market gastronomy lies a relentless subtropical climate where humidity and mold present persistent challenges in aging budget hotels. Escaping the confusing underground concourses of Taipei Main Station requires street-by-street location intelligence. Here is an unvarnished field guide to selecting healthy, strategically positioned lodging and navigating local customs.
Taipei Day 1 Arrival Blueprint: Taoyuan Airport Express, Beef Noodle Alleys, and Dadaocheng Sunset
From boarding the 36-minute purple express train at Taoyuan Airport to navigating Taipei Main Station's underground maze, mastering local beef noodle lexicon, and watching sunset at Dadaocheng Wharf. A step-by-step masterclass for effortless settlement in your first 24 hours.
Taipei Day 2: National Palace Museum, Dihua Street Heritage, Xiangshan Sunset, and Raohe Night Market
Day 2 bridges imperial grandeur and vibrant urban culture: morning encounters with jade treasures at the National Palace Museum, dried fruit and tea apothecary strolls in historic Dihua Street, golden-hour hikes up Elephant Mountain facing Taipei 101, and Michelin-acclaimed pepper bun feasts inside Raohe Night Market.
Taipei Day 3: Fu Hang Soy Milk, Taipei 101 Heights, Yongkang Street Shopping, and Airport MRT Departure
A seamless grand finale to your Taipei journey: award-winning savory soy milk at Fu Hang, historic sake distillery warehouses turned art galleries at Huashan 1914, world-famous soup dumplings at Din Tai Fung beside soaring views atop Taipei 101, handcrafted artisan tea and pineapple cake shopping in Yongkang Street, followed by luggage-free transit via Taipei Main Station In-Town Check-in directly to Taoyuan Airport.
Living Slow in Chiang Mai: 3rd-Wave Roasteries and $45 Boutique Havens
Comparing Nimman and Old City living hubs, unlocking automatic Agoda weekly stay markdowns, and mastering PromptPay QR with Bolt transit across northern Thailand.
Nha Trang Cam Ranh Playbook: Securing $100 Private Oceanfront Pool Villas
Comparing Cam Ranh resort sanctuaries and downtown Nha Trang, locking in 45-day early-bird rates on luxury villas, and mastering private transfers with Grab safety rules.
Leaving Hakata for the Misty Foothills of Mount Yufu
How to lock in Car 1 panoramic seats on the Yufuin no Mori, comparing Lake Kinrin vs. Okuyufuin valleys, and optimizing kaiseki half-board packages.
Ditching Taipei's Drizzle for Southern Sunshine in Ninety Minutes
How to unlock the foreigner-exclusive THSR buy-one-get-one bullet train deal, comparing Pier-2 vs. Formosa Boulevard, and scoring $45 design harbor suites.
Chasing Kota Kinabalu World-Class Sunsets: $100 Oceanfront Sanctuaries and Firefly Rivers
An insider guide comparing Tanjung Aru and Sutera Harbour enclaves, claiming front-row sunset perches, booking mangrove firefly boats, and mastering Ringgit currency rules.
Under the Infinite Vault of Central Asian Stars: A Tactical 6-Day Overland Guide to Mongolia's Gobi Steppe
Soviet Furgons vs. modern 4WDs, auditing traditional gers against heated glamping lodges, and cutting expedition costs by 50% via group assembly.
Route 58 Ocean Highway and Onna Luxury Coves: A Tactical Driving and Resort Guide to Okinawa
Cutting airport rental queues with smart split-stays, booking oceanfront Onna suites below peak rates, and dodging resort parking fees and DCC markups.
Okinawa Onna Coast Luxury Beach Resorts & Kerama Blue Playbook
From premier oceanfront resort sanctuaries along the Onna coastline to crystalline diving expeditions in the Kerama Islands, an authoritative four-day playbook for island indulgence.
Mactan Coral Reef Enclaves and the 3 AM Oslob Run: A Tactical Luxury Guide to Cebu
Navigating midnight airport taxi queues, factoring in 22% VAT and service charge surprises, auditing Mactan's private reef resorts, and minimizing Oslob expedition fatigue.
Hong Kong 72-Hour Skyline Playbook: Star Ferry and Sheung Wan Boutiques
Skip the turnstiles straight onto the Airport Express, fund mobile Octopus cards instantly, and choose spacious Sheung Wan boutique lofts over cramped Tsim Sha Tsui shoebox rooms for a smarter 72-hour Hong Kong trip.
Hong Kong Central & Sheung Wan Boutique Haven & Star Ferry Playbook
From the nostalgic romance of century-old Star Ferry crossings to chic boutique design havens in Sheung Wan and SoHo culinary alleys, an authoritative four-day Hong Kong guide.
Hong Kong District Field Guide: Tsim Sha Tsui vs Sheung Wan vs Fortress Hill, Dodging Mansions, and Diner Etiquette
Behind Hong Kong's dazzling skyline lies one of the world's most hyper-dense urban environments, where astronomical real estate costs have spawned notorious windowless micro-rooms. Escaping the elevator queues and safety liabilities of Kowloon's aging mansions requires strategic district selection. Here is an unvarnished field guide to securing functional, secure lodging and navigating local dining culture.
Hong Kong Day 1 Arrival Playbook: 24-Minute Airport Express, Dim Sum Etiquette, and Harbour Sunset
Mastering the 24-minute Airport Express to Central versus the scenic Cityflyer bus, authentic dim sum teacup rinsing rituals, and evening strolls along Victoria Harbour. A veteran field guide to your first 24 hours.
Hong Kong Day 2 Playbook: Morning Peak Tram, Soho Escalators, Star Ferry, and Harbour Lights
Beat the crowds on an early morning Peak Tram ascent, glide through Soho on the worlds longest outdoor escalator, savor crisp roast goose, and cross Victoria Harbour on the historic Star Ferry for the iconic Symphony of Lights.
Hong Kong Day 3 Finale: Traditional Pushcart Dim Sum, Sham Shui Po, M+ Museum, and In-Town Check-In
Start your final morning with authentic trolley dim sum, discover the authentic street pulse of Sham Shui Po, relax at the West Kowloon M+ waterfront, and use in-town check-in at Hong Kong Station for a baggage-free sprint to your flight.
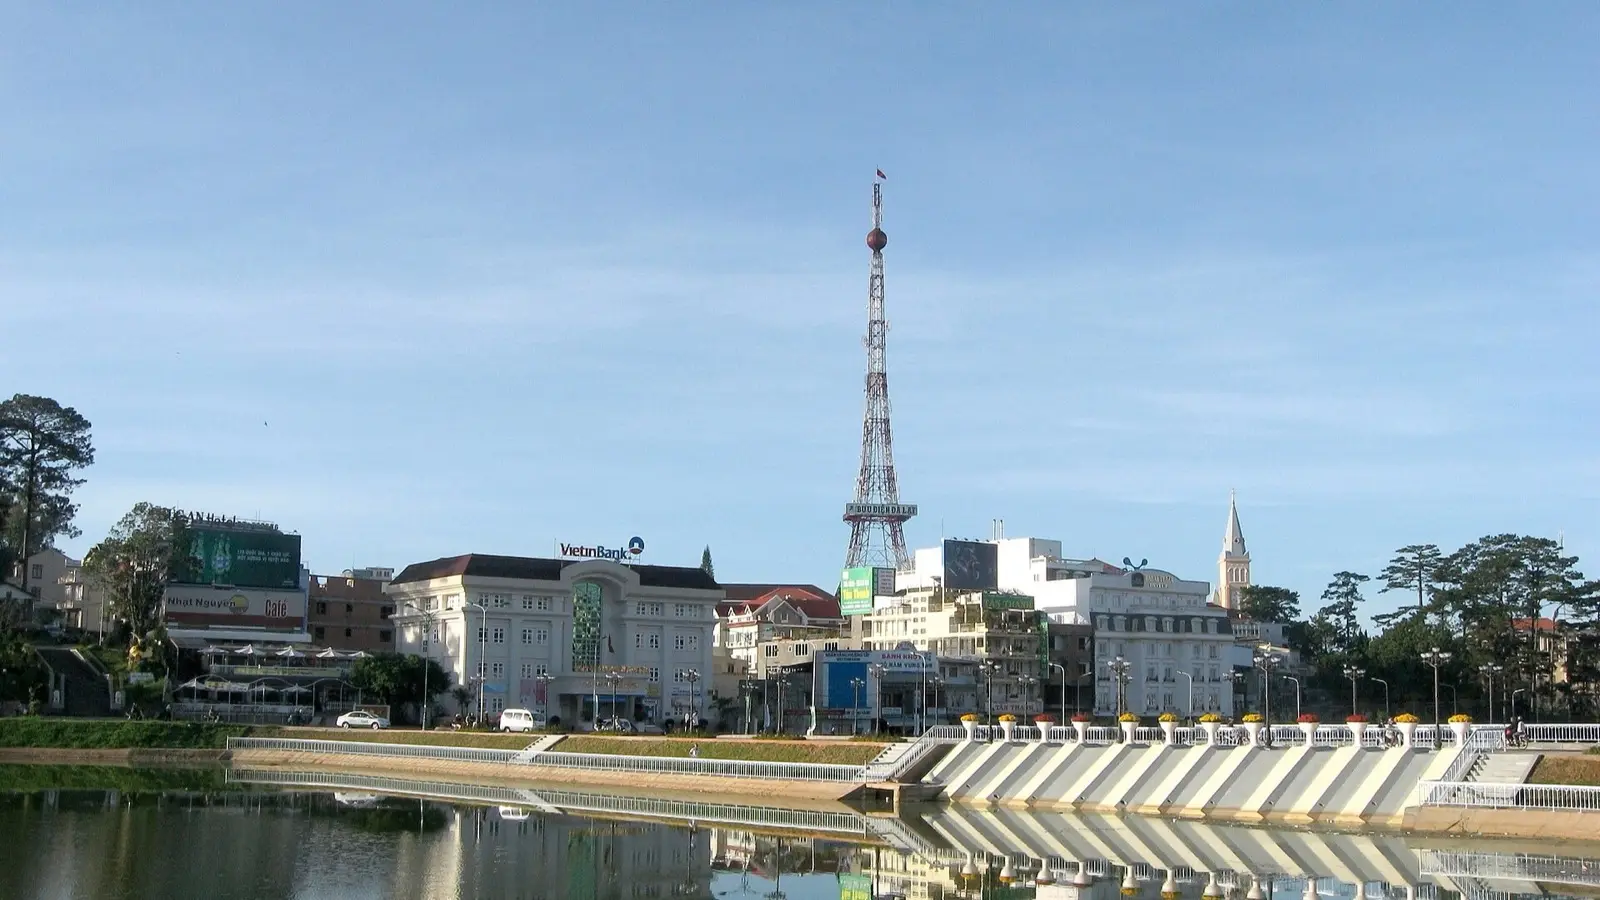
Da Lat Highland Escape: French Colonial Heritage Villas and Pine Forest Retreats
Wake to 14C morning mountain air, dodge grueling 7-hour sleeper bus mountain passes with a 45-minute domestic hop, and trade noisy central motels for 1920s French governor villas tucked beneath whispering pines.
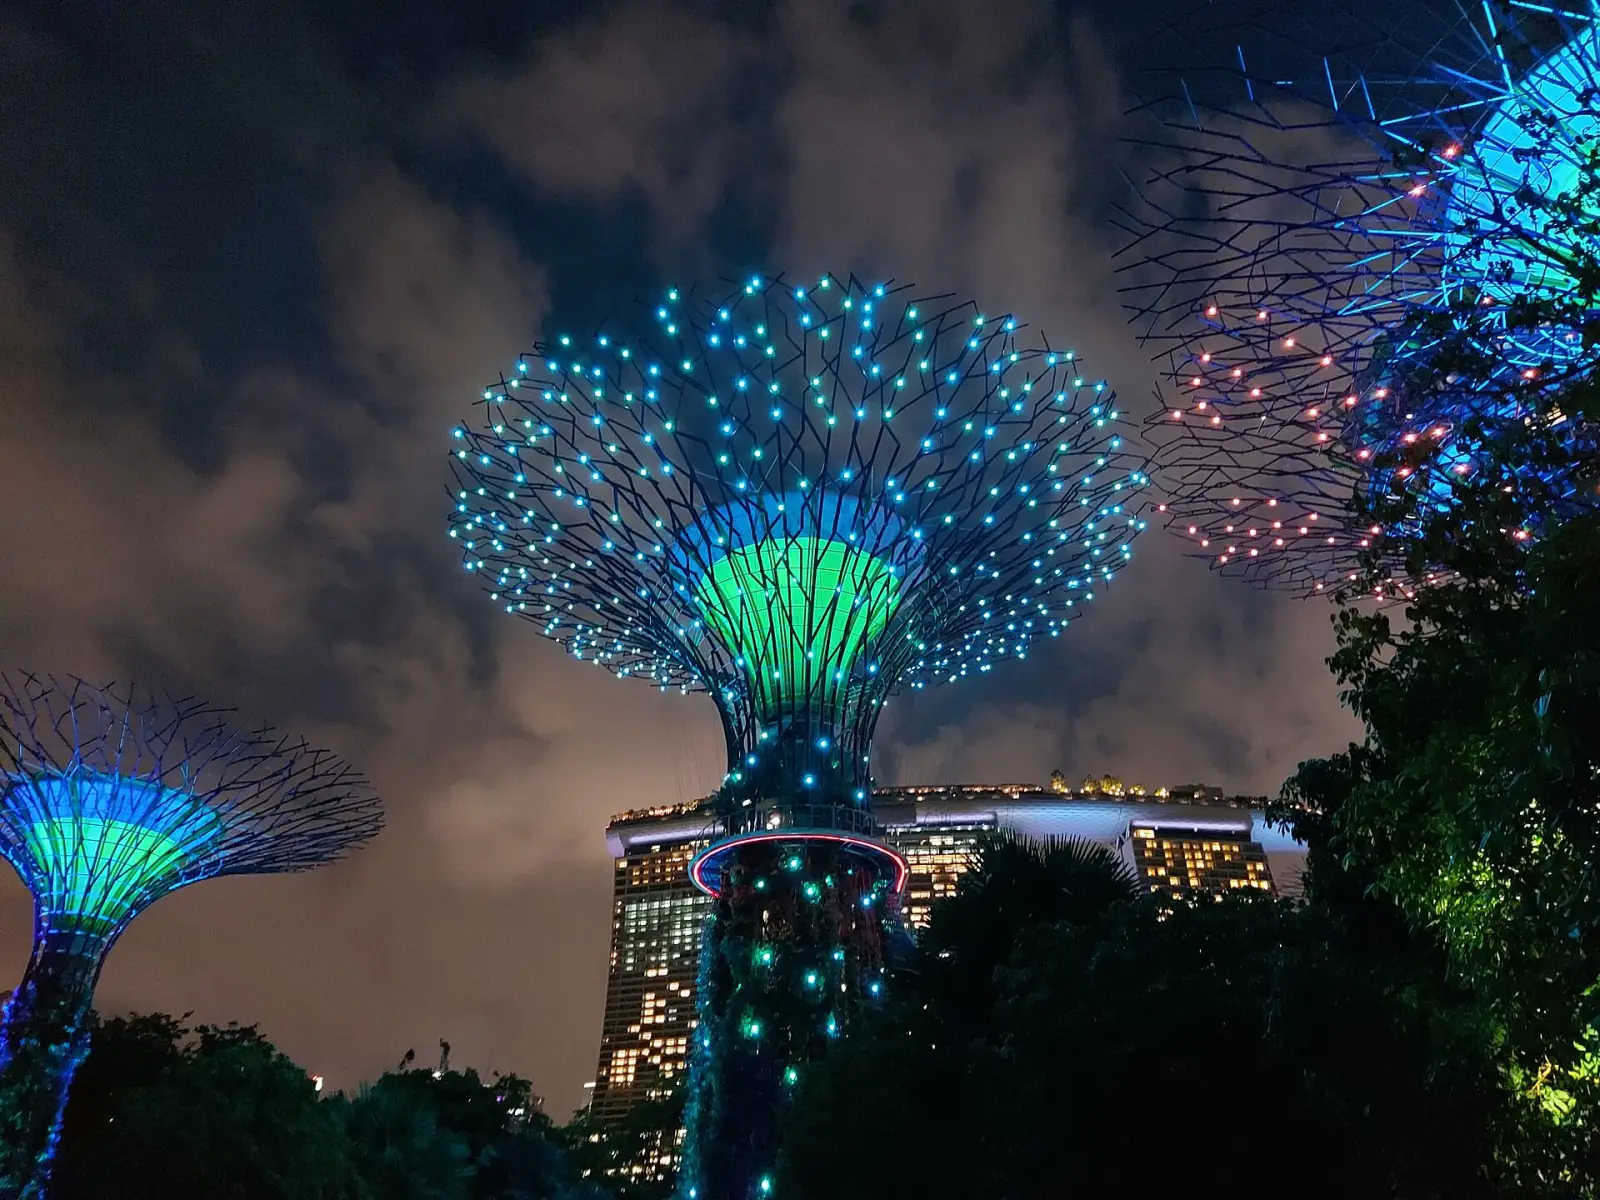
Singapore 72-Hour Skyline Playbook: Marina Bay Sands and Changi Jewel
Skip transit card lines with contactless bank cards, drop bags at Jewel before heading into town, and deploy a split-stay strategy that captures Marina Bay Sands pool access without draining your entire vacation budget.
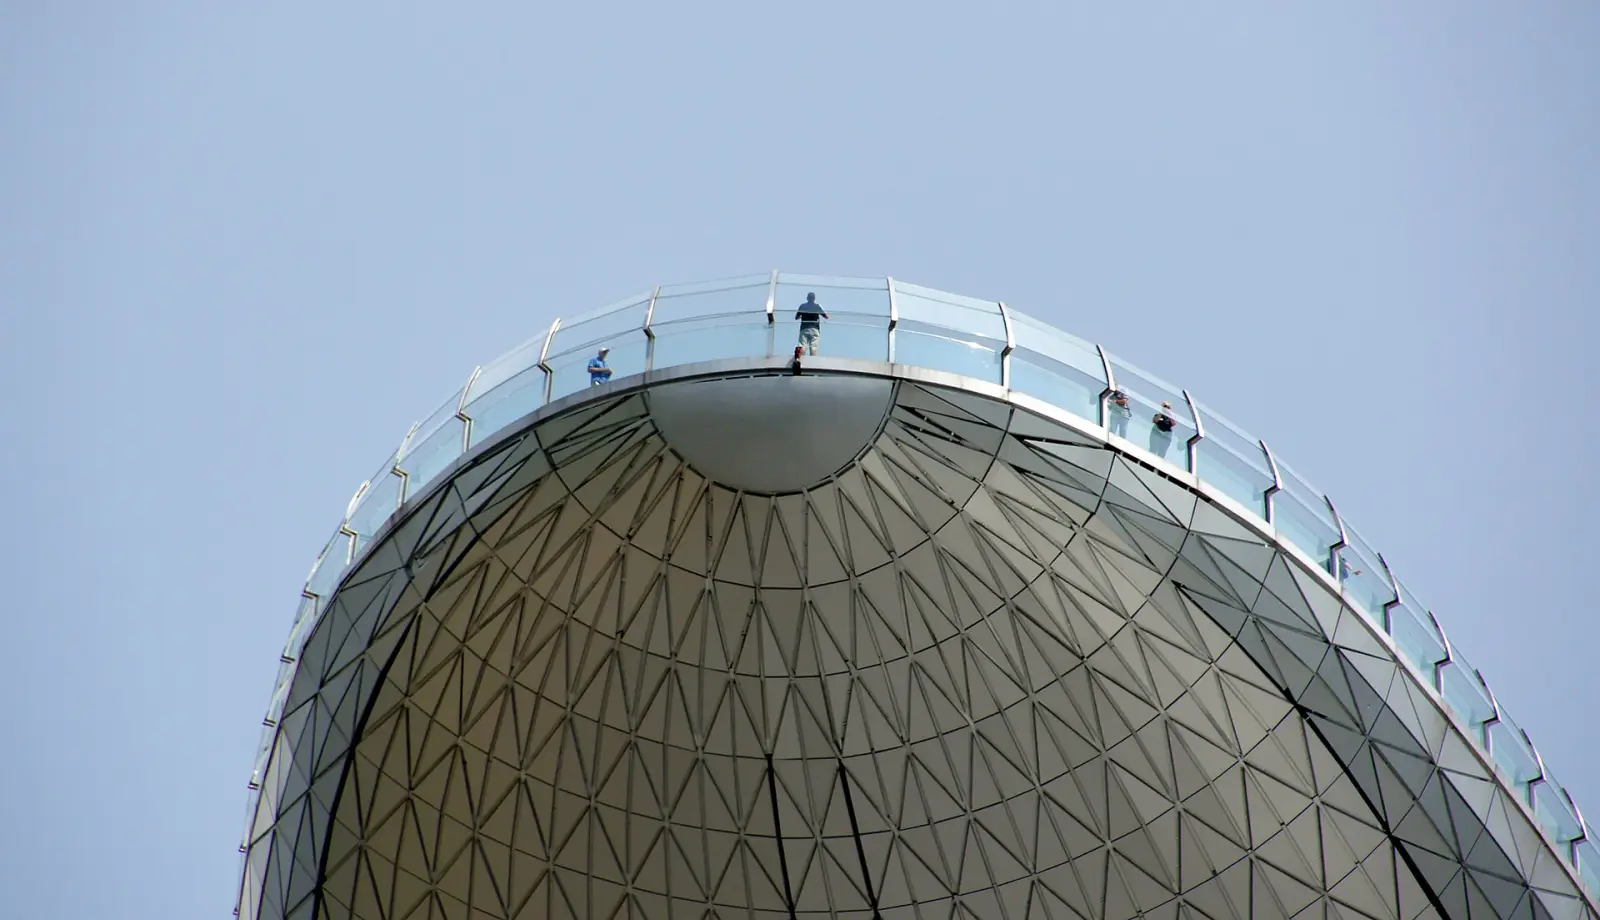
Singapore Marina Bay Luxury & Tanjong Pagar Heritage Shophouse Playbook
From suspended 200-meter infinity pool vistas over Marina Bay to heritage shophouse design retreats in Tanjong Pagar and UNESCO hawker feasts, an authoritative Singapore playbook.
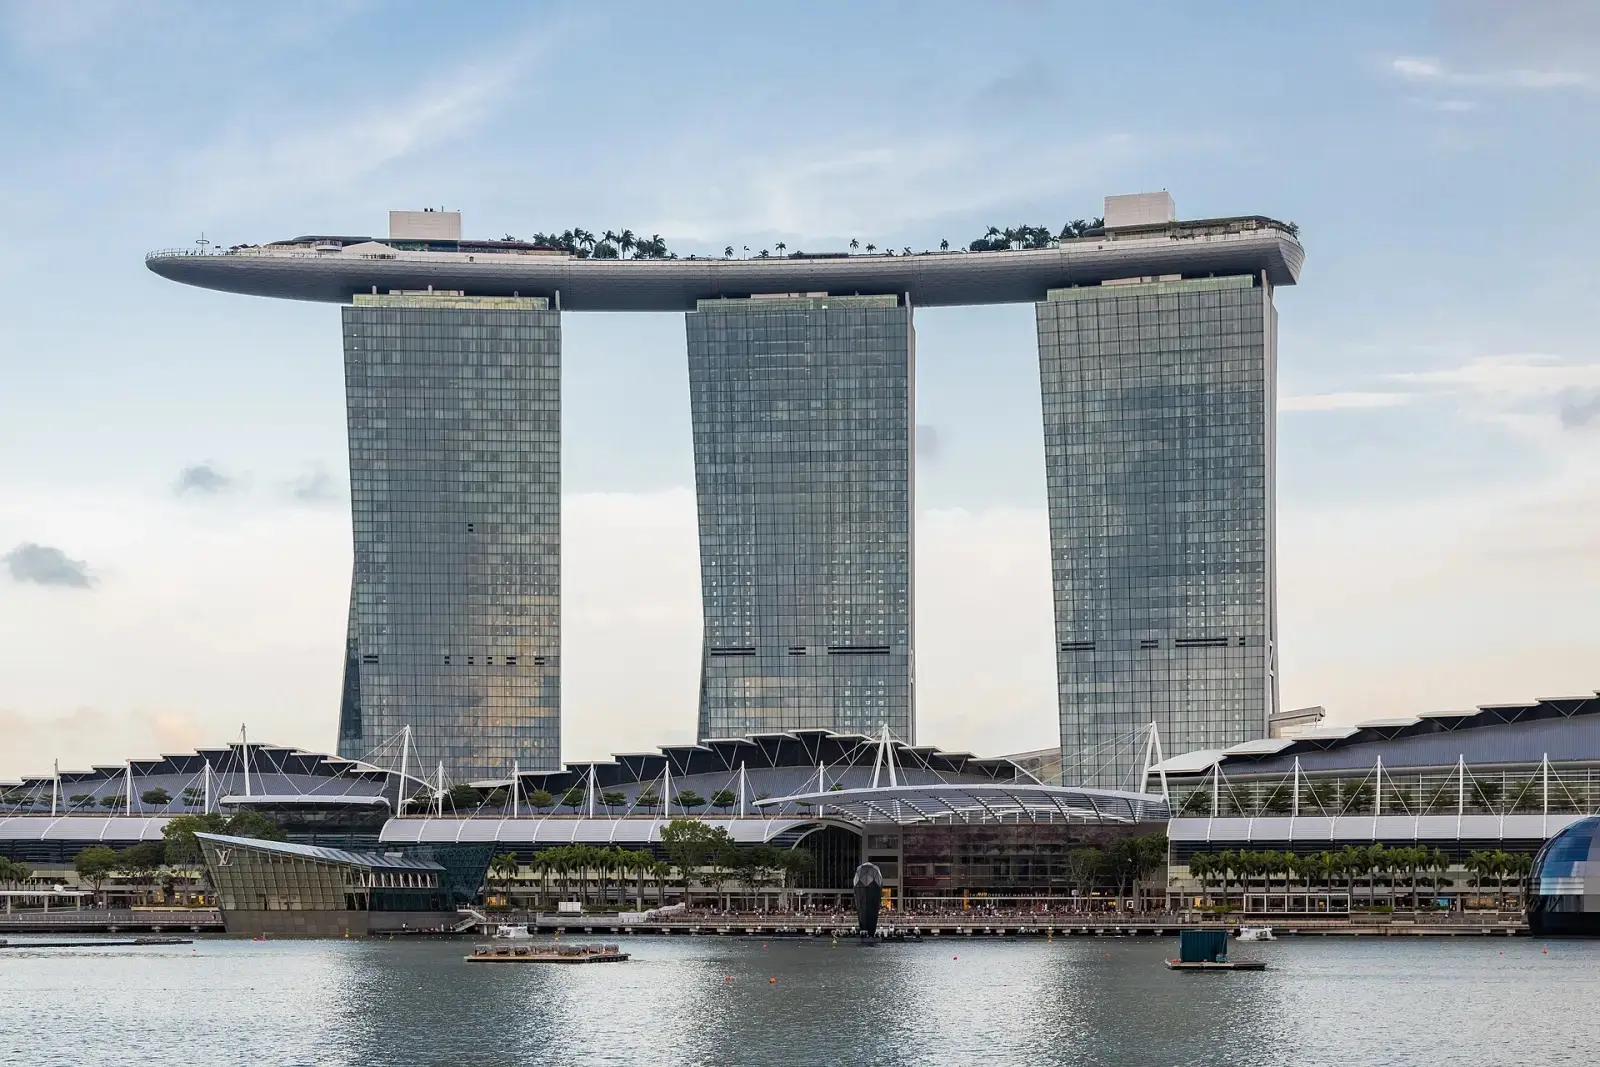
Singapore Day 1 Arrival Playbook: Changi Jewel Waterfall, SimplyGo MRT, and Hawker Chope Etiquette
Navigating Changi's Jewel Rain Vortex, tapping into the MRT network using foreign contactless credit cards via SimplyGo, mastering hawker center tissue packet reservations, and sunset along Marina Bay. A field guide to your first 24 hours.
Singapore Day 2 Playbook: Cloud Forest Waterfall, Supertree Skyway, Chinatown Hawker, and Spectra Lights
Marvel at the 35-meter indoor waterfall inside the misty Cloud Forest, cross the OCBC Skyway between towering Supertrees, savor Michelin-recognized chicken rice at Maxwell, explore Kampong Glam, and end with the Spectra waterfront light show.
Singapore Day 3 Finale: Kaya Toast Breakfast, Botanic Gardens, Jewel 40m Waterfall, and Early Check-In
Savor iconic charcoal kaya toast with soft-boiled eggs, explore VIP orchids at the UNESCO Singapore Botanic Gardens, collect pandan cakes, and admire the 40-meter Rain Vortex waterfall before seamless early check-in at Jewel Changi Airport.
Jeju Coastal Drive: Seogwipo Oceanfront Pool Villas and Gotjawal Forests
Discover why cruising the gentle Pyeonghwa-ro bypass easily trumps dangerous mountain passes, master zero-deductible rental car insurance safeguards, and trade generic resort hotels for secluded private pool sanctuaries in Seogwipo.
Jeju Coastal Roadtrip & Basalt Cottage Masterclass: Aewol Sunsets, Super CDW Hacks, and Local Butcher Audits
Leaving Jeju Airport behind to hit the coastal curves of Aewol, the raw geological beauty of black volcanic rock against turquoise surf unfolds. This field guide bypasses crowded Instagram traps to audit private basalt courtyard cottages, explain why zero-deductible Super CDW insurance is mandatory on rural roads, and steer you toward authentic haenyeo diver kitchens.
Hanoi 72-Hour Skyline Playbook: French Colonial Heritage and Old Quarter Roasteries
Morning mist rising over Hoan Kiem Lake, the bittersweet aroma of egg coffee, and century-old French colonial villas. A curated blueprint for navigating Hanoi without noise, exhaustion, or tourist traps.
Phuket Andaman Skyline Playbook: Kata Noi Oceanfront Villas and Old Town Heritage
Leaving behind the frantic nightlife of Patong for the pristine granite coves of Kata Noi and Kamala. An insider guide to cliffside Andaman infinity pools, historic Old Town Sino-Portuguese architecture, and seamless island exploration.
Seoul Heritage & Creative Scene: Bukchon Hanoks, Seongsu Boutiques and Han River Sunsets
From the 43-minute AREX express from Incheon Airport to tranquil Hanok courtyard stays, industrial red brick roasteries in Seongsu, and Banpo Han River instant ramen picnics.
Seoul Hanok Heritage & Seongsu Craft Alleys: Century-Old Tiles, Courtyard Tea, and Urban Contrasts
Amid the relentless futuristic pace of contemporary Seoul, stepping through the wooden gate of a century-old hanok courtyard offers an astonishing immersion in quietude. From booking private heritage residences in Bukchon and Seochon to navigating Seongsu craft coffee roasteries, this field guide audits real costs, noise curfews, and transit hacks.
Seoul Day 1 Blueprint: 43-Min AREX Airport Express, Bukchon Hanok Quiet Hours, and Gwangjang Food Crawl
The definitive first 24-hour Seoul playbook: mastering the 43-minute AREX airport express, navigating Bukchon quiet hours, savoring sizzling Gwangjang mung bean pancakes, and ending with a serene midnight stroll along Cheonggyecheon stream.
Seoul Day 2 Masterclass: Royal Palace Pageantry, Seochon Brass Coins, Seongsu Scene, and Namsan Heights
An extraordinary second day across Seoul: witnessing the solemn Changing of the Royal Guard at Gyeongbokgung, bartering antique brass coins for lunch in Seochon, discovering Seongsu's industrial-chic design universe, and capping the twilight with riverside instant ramen and glittering N Seoul Tower views.
Seoul Day 3 Finale: Yeonnam Green Line, The Hyundai K-Fashion, and In-Town Airport Fast-Track
The ultimate finale in Seoul: a morning stroll down the lush Gyeongui Line Forest Trail, browsing trendsetting designer boutiques in Hongdae, experiencing the architectural wonder of The Hyundai Seoul, and utilizing Seoul Station's in-town check-in to glide through Incheon Airport departure queues hands-free.
Kuala Lumpur Skyline Stays: Petronas View Infinity Pools and Jalan Alor Street Food
From the 28-minute KLIA Ekspres airport transit to luxury twin tower infinity pool stays, Jalan Alor charcoal satay feasts, and the vibrant rainbow steps of Batu Caves.
Macau Heritage & Cotai Strip: 400 Years of Portuguese Culture and Luxury Stays
Discover Macau where Portuguese stone facades meet dazzling Cotai skylines. Master the 40-minute HZMB cross-sea bus transit, free casino shuttle routes, and authentic egg tarts in peaceful Coloane Village.
Sydney Harbour & Coastal Trails: Opera House Sunsets and the Manly Ferry Playbook
Experience Sydney where modern sail architecture meets raw Pacific coastlines. Navigate the 30-minute Manly ferry cruise under A$10, trek the dramatic Bondi to Coogee clifftop path, and taste third-wave flat whites in Surry Hills.
Busan Ocean Escape: Haeundae Blue Line Park, Gwangalli Nightlines and KTX Express Travel
Experience South Korea's vibrant coastal capital. In just 2 hours and 15 minutes by KTX from Seoul, step aboard the scenic Haeundae Sky Capsule gliding above turquoise waves, witness Saturday night drone spectacles over Gwangalli Bridge, and savor authentic seafood at Jagalchi.
Busan Oceanfront & Coastal Rail Masterclass: Gwangan Bridge Sunsets, Jagalchi Alleys, and Split-Stay Planning
From the glittering bridge views of Gwangalli to the high-rise luxury resorts of Haeundae and the salt-crusted alleys of Jagalchi, Busan's coastal identity spans dramatic contrasts. This field audit delivers actionable advice on hotel split-stays, booking the Blue Line sky capsule before sold-out surges, and navigating local fish market markups without awkward confrontation.
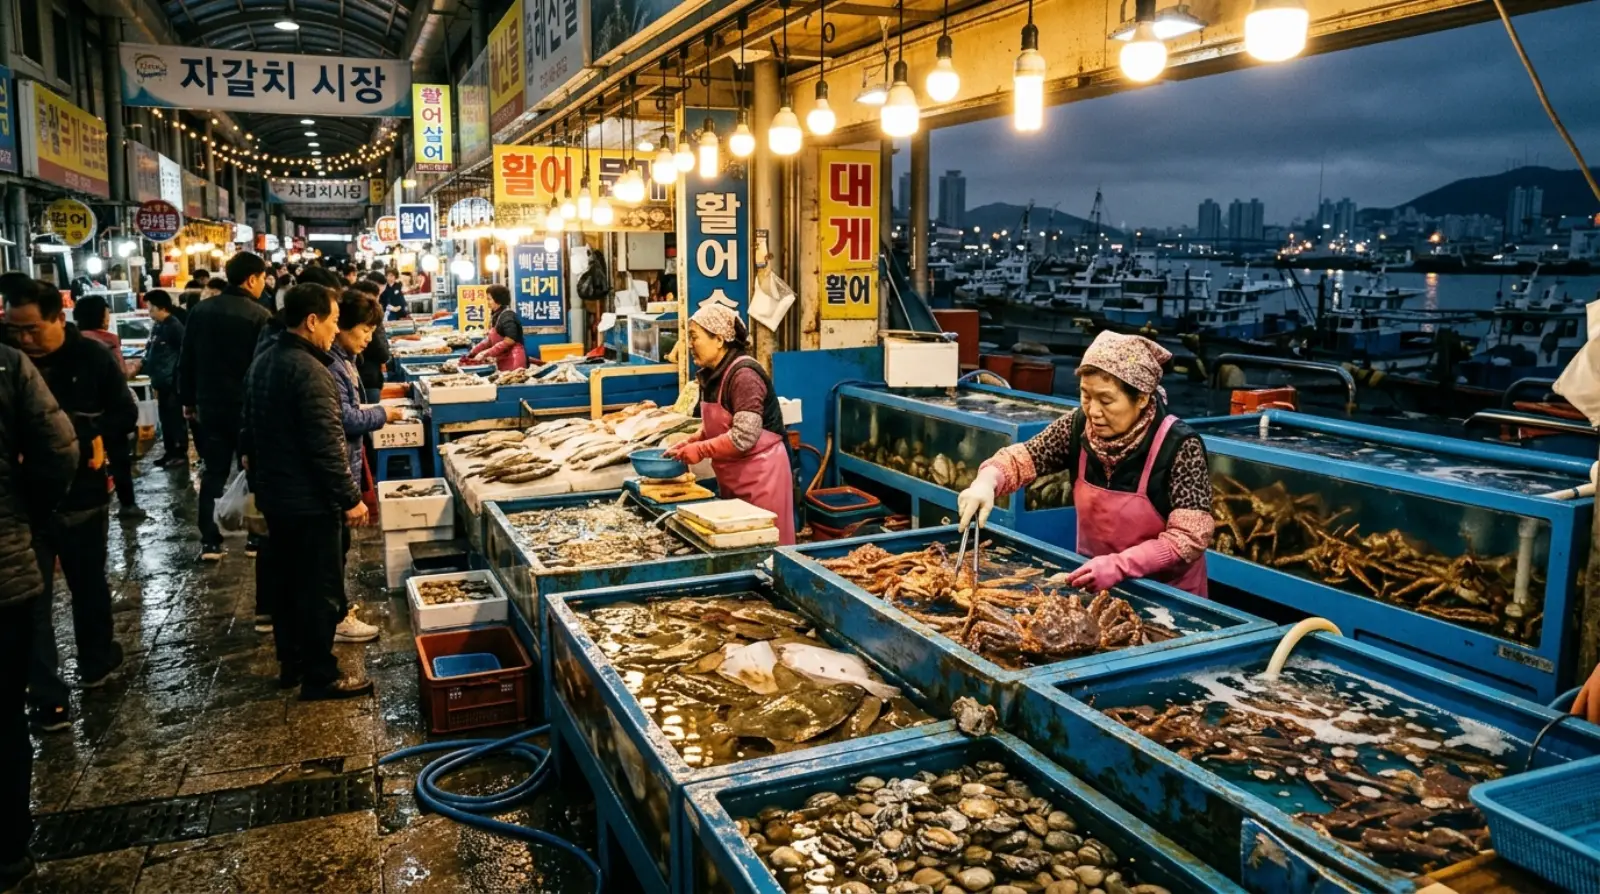
Busan Day 1 Blueprint: 2-Hour KTX Transit, Jagalchi Seafood Alleys, and Bupyeong Night Feasts
The moment the KTX glides into Busan Station after a swift 2-hour-15-minute journey from Seoul, the salty ocean breeze announces your arrival. From a steaming bowl of pork soup in Choryang to the raw energy of Jagalchi fish market and the sizzling nighttime stalls of Bupyeong Market, here is your definitive first 24 hours in Busan.
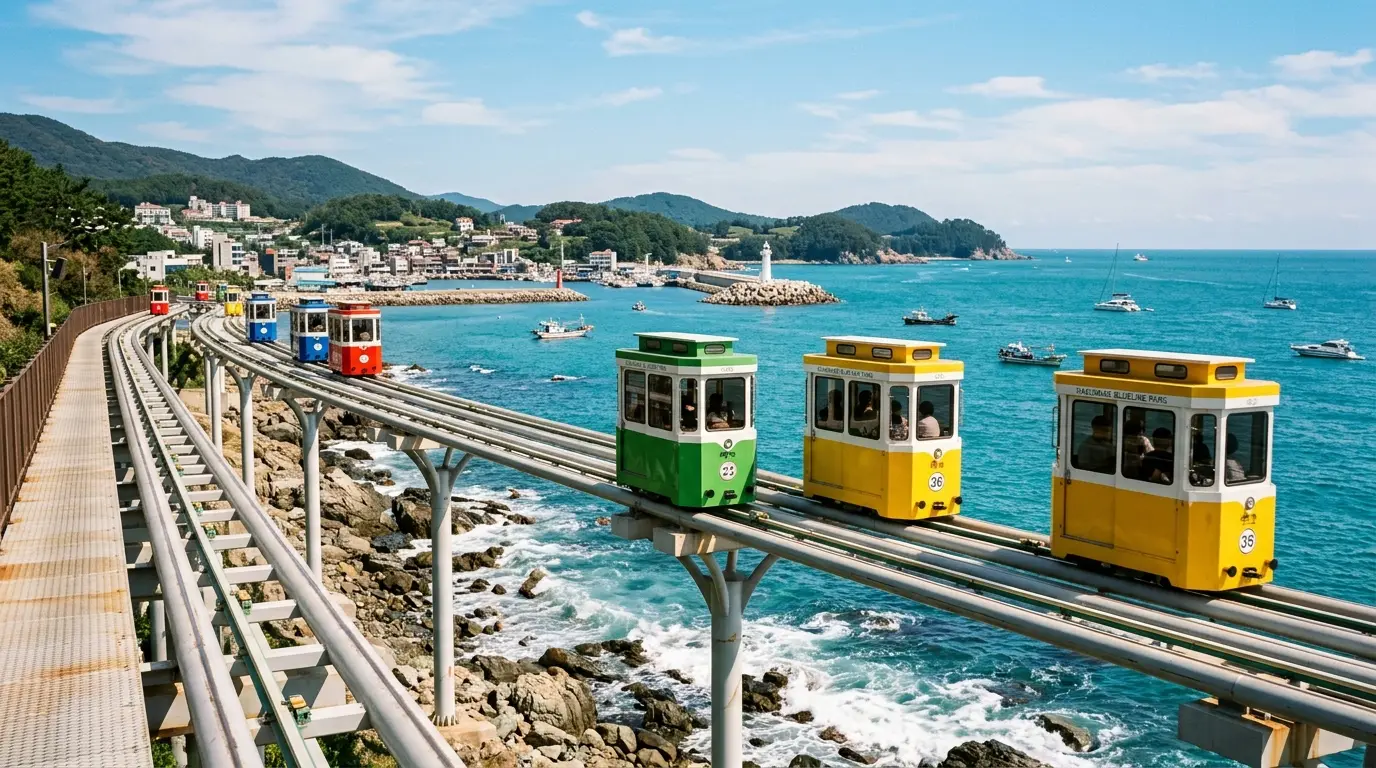
Busan Day 2 Coastal Blueprint: Sky Capsule Ocean Vistas, Cheongsapo Clams, and Marine City Night Reflection
Gliding 10 meters above coastal pine groves inside a retro Haeundae Sky Capsule, savoring butter-drenched grilled shellfish by Cheongsapo's twin lighthouses, listening to crashing waves at the cliffside Haedong Yonggungsa Temple, and capturing mirror-like skyscraper reflections at The Bay 101: your definitive Day 2 along Busan's eastern coastline.
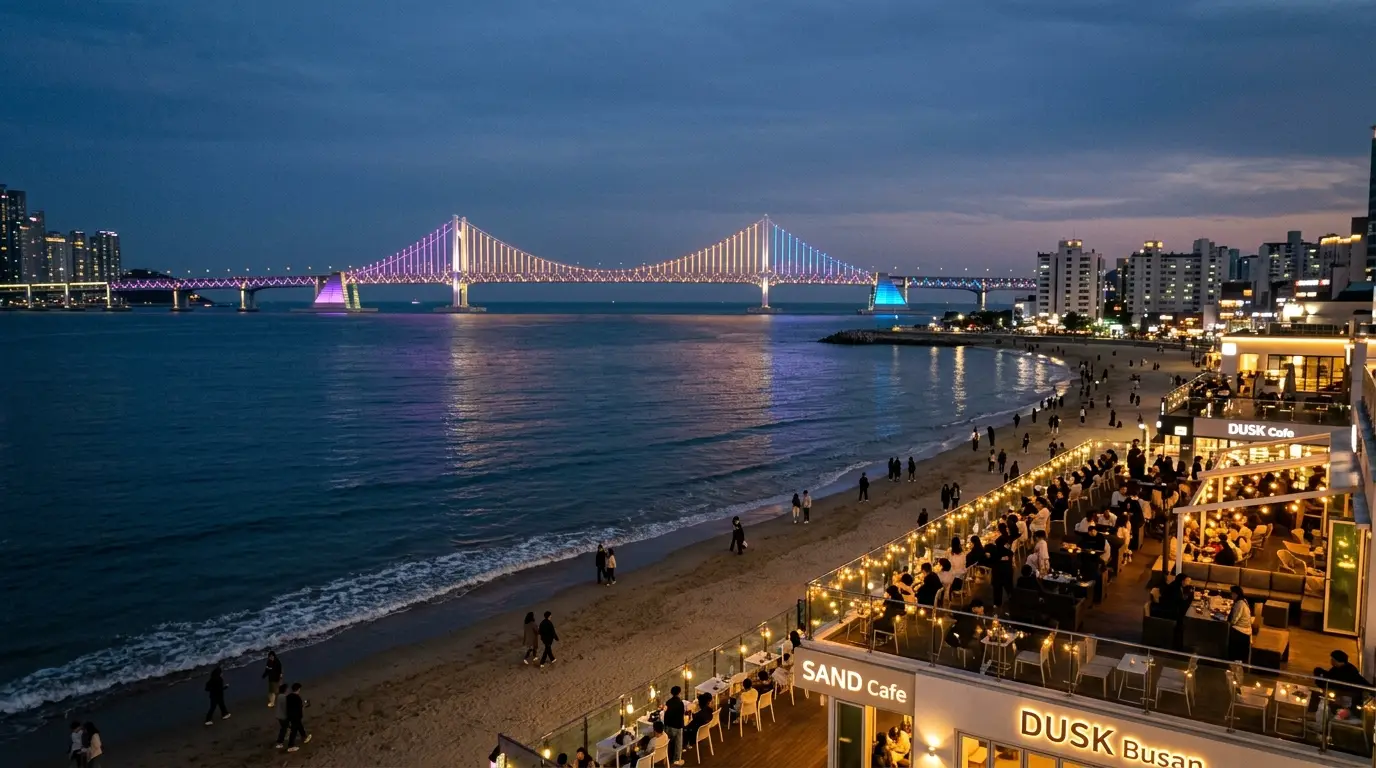
Busan Day 3 Cultural Blueprint: Gwangalli Bridge Brunches, Gamcheon Alleys, and Station Departure
Savoring artisanal pour-over coffee facing the gleaming silver cables of the Gwangan Diamond Bridge, navigating the pastel labyrinth of Gamcheon Culture Village, strolling along the cliffside paths of Yeongdo Huinnyeoul Village, and packing vacuum-sealed artisanal fishcakes at Busan Station: the definitive final chapter of your 3-day Busan journey.
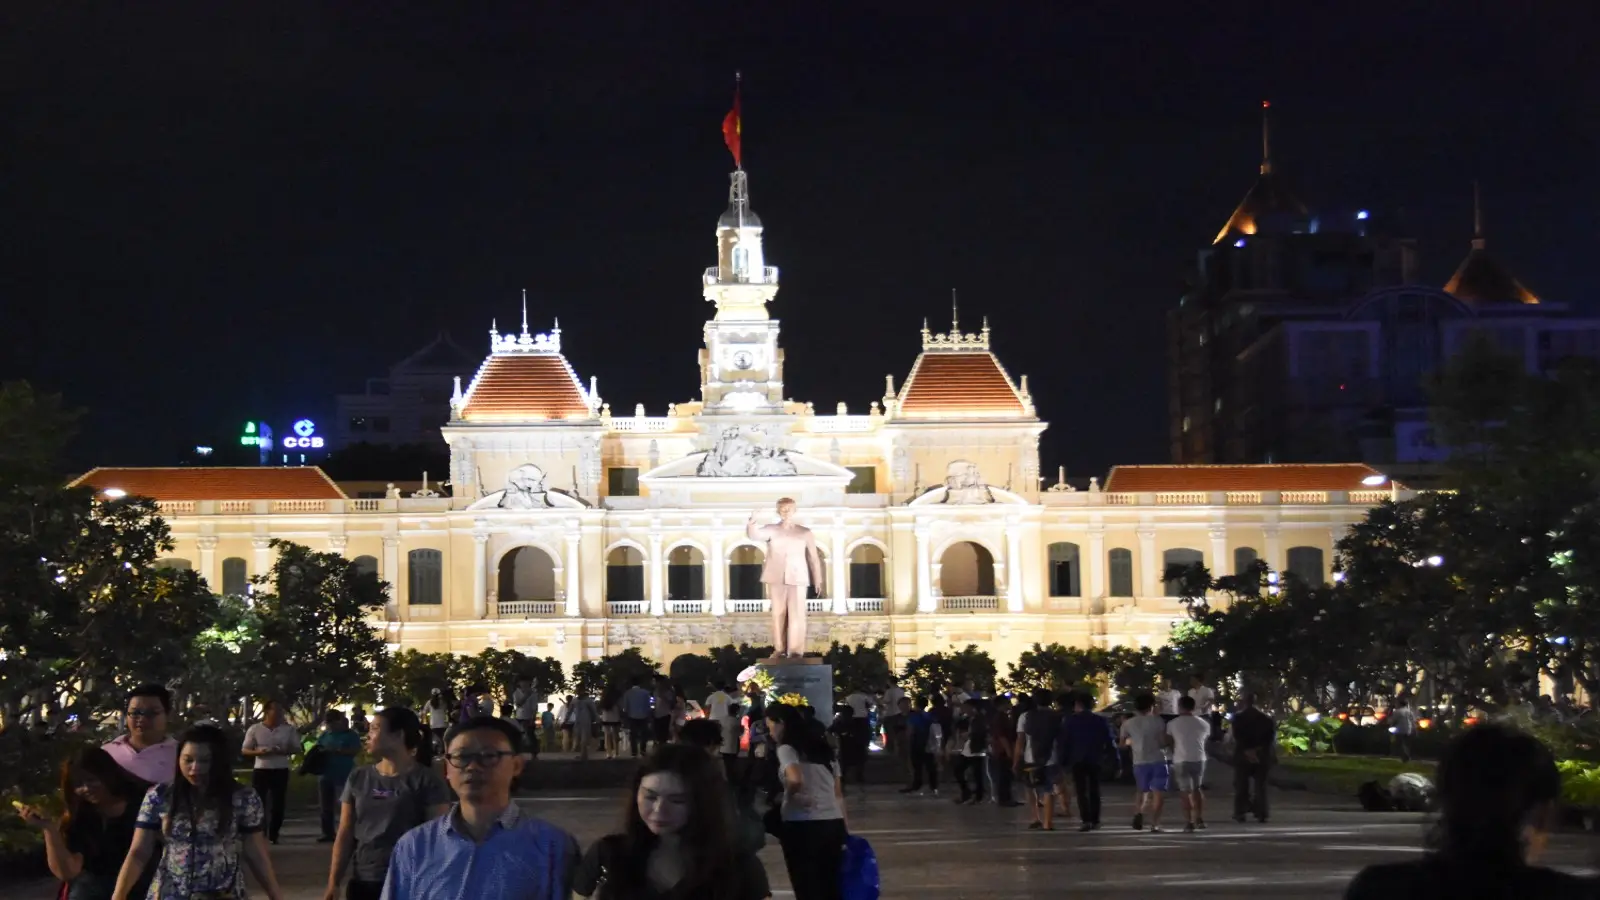
Ho Chi Minh City Heritage: French Architecture, Cafe Apartments and Saigon River Sunsets
Discover Vietnam's pulsing commercial metropolis where broad colonial boulevards meet creative third-wave roasteries. Explore the Gustave Eiffel-designed Central Post Office, the 9-story cafe collective at 42 Nguyen Hue, and sunset boat cruises along the Saigon River.
Nagoya Urban Rhythm & Ghibli Park: Hitsumabushi Dining and 72-Hour Meieki Playbook
Strategically located between Tokyo and Osaka, Nagoya blends cutting-edge industrial innovation with deep samurai heritage. Discover how to ride the 28-minute mu-SKY express from Chubu Centrair Airport, navigate high-demand Ghibli Park bookings, savor multi-step charcoal hitsumabushi eel, and photograph illuminated skylines at Oasis 21.
Dubai Skylines & Crimson Dunes: 72-Hour Luxury Guide from Burj Khalifa to Old Dubai Creek
Rising from golden desert shores into the future, Dubai seamlessly fuses hyper-modern architecture with authentic Arabian heritage. Journey through 828-meter panoramas atop Burj Khalifa, front-row views of choreographed Dubai Fountains, exhilarating desert dune bashing, and evocative cross-creek voyages aboard traditional wooden abras for a single dirham.
Oahu Island Drive & Waikiki Playbook: Dodging Resort Fees and North Shore Surf Stays
Beyond the postcard allure of Waikiki lies one of the most fee heavy hotel markets on earth. Learn how to calculate surprise resort surcharges, navigate Hanauma Bay conservation permits, secure reasonable parking rates, and embark on a panoramic coastal journey through Oahu eastern cliffs and North Shore shrimp trucks.
Guam Tumon Bay Playbook: Beachfront Family Stays and Tax-Free Hacks
Just a short four-hour flight from major East Asian hubs, Guam offers calm turquoise lagoons and barrier reefs. Discover how to evade airport transit price gouging, choose between beachfront luxury towers and sprawling waterpark resorts in Tumon, and unlock southern coastal heritage and zero-sales-tax retail bargains.
Saipan Lagoon & Grotto Escape: Managaha Coral Cay and Northern Cliffs
Encircled by seven shades of turquoise water, Saipan is the crowning sanctuary of the Northern Mariana Islands. Master the logistics of taking a 15-minute speedboat to Managaha Island, descend the 112 limestone steps into the ethereal sapphire light of The Grotto, and drive through historical coastal monuments at Banzai Cliff and Bird Island.
Manila 72-Hour Contrast: 400-Year Intramuros Fortress and Modern BGC Skylines
Beyond the congested traffic lies a city of dramatic historical dualities. Learn how to navigate Ninoy Aquino International Airport arrivals using official Grab kiosks, pedal bamboo bicycles atop 400-year-old stone walls in Intramuros, photograph fiery Pacific sunsets over Manila Bay, and unwind in the safe, pedestrianized lifestyle corridors of Bonifacio Global City.
Los Angeles California Dreaming: Santa Monica Pier & Griffith Sunset Playbook
Sprawling beneath endless Southern California sunshine, Los Angeles is a patchwork of cinematic landscapes. Conquer the notorious LAX-it rideshare and rental car shuttle maze, secure sunset perches overlooking downtown skylines from Griffith Observatory, cruise beachside paths from Santa Monica to Venice, and reserve timed admission to the hilltop Getty Center.
Prague 72-Hour Fairy Tale: Charles Bridge Sunrise and Bohemian Castle Heights
Draped in Gothic mystery and Baroque elegance, Prague is Europe best-preserved open-air museum. Master the early morning rhythm to experience Charles Bridge in silence, evade notorious currency exchange scams near Wenceslas Square, explore St. Vitus Cathedral atop Prague Castle, and drink fresh unpasteurized Pilsner Urquell where beer is cheaper than water.
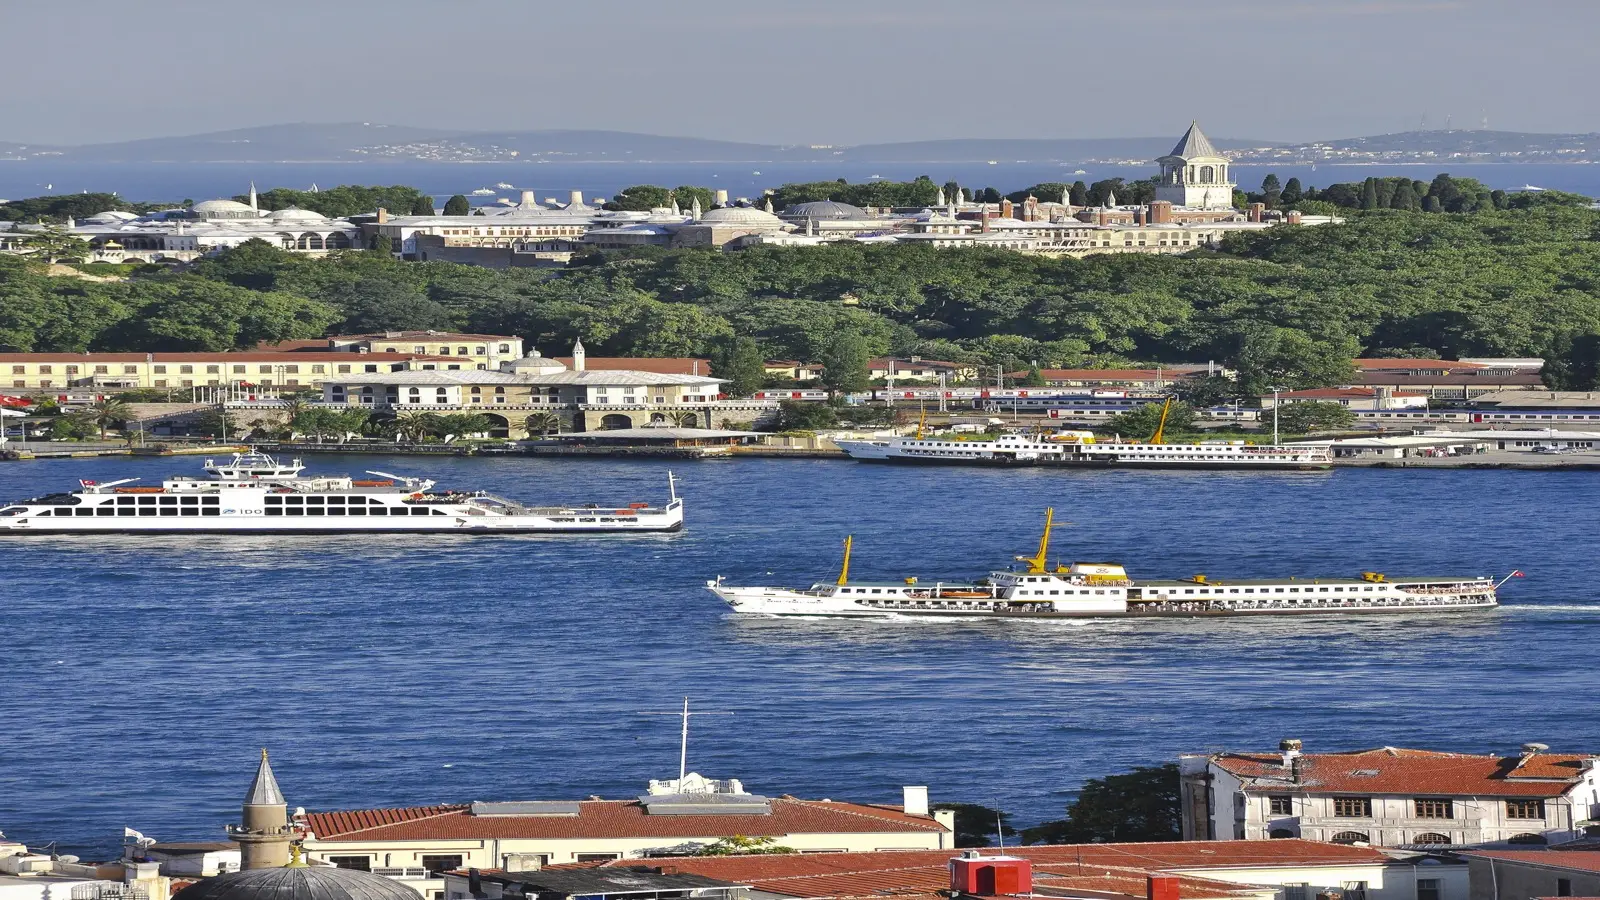
Istanbul Bosphorus Crossroads: Hagia Sophia and Two Continents in 72 Hours
Spanning two continents separated by the deep currents of the Bosphorus Strait, Istanbul is a breathtaking crossroad of empires. Discover how to ride Havaist express airport coaches, observe respectful dress codes inside Hagia Sophia, negotiate with merchant masters across 4,000 stalls in the Grand Bazaar, and cross between Europe and Asia on scenic commuter ferries.
The Flight Pricing Myth: Dismantling Incognito Hacks and Mastering Split Routing
An investigative deep dive into airline revenue management algorithms, exposing why incognito mode fails while multi-city open-jaw routing and baggage decoupling slash flight costs by over 30%.
Travel Debit Cards vs Premium Credit Cards: The Mathematical Break-Even Blueprint
A rigorous financial breakdown comparing top multi-currency travel debit cards against premium credit card travel rewards, highlighting standalone ATM traps and hotel deposit holds.